The Won't Get Fooled Again Act
A Comprehensive Framework for Converting Failed Financial and Artificial Intelligence Institutions into Mission-Driven Public Utilities
Executive Summary
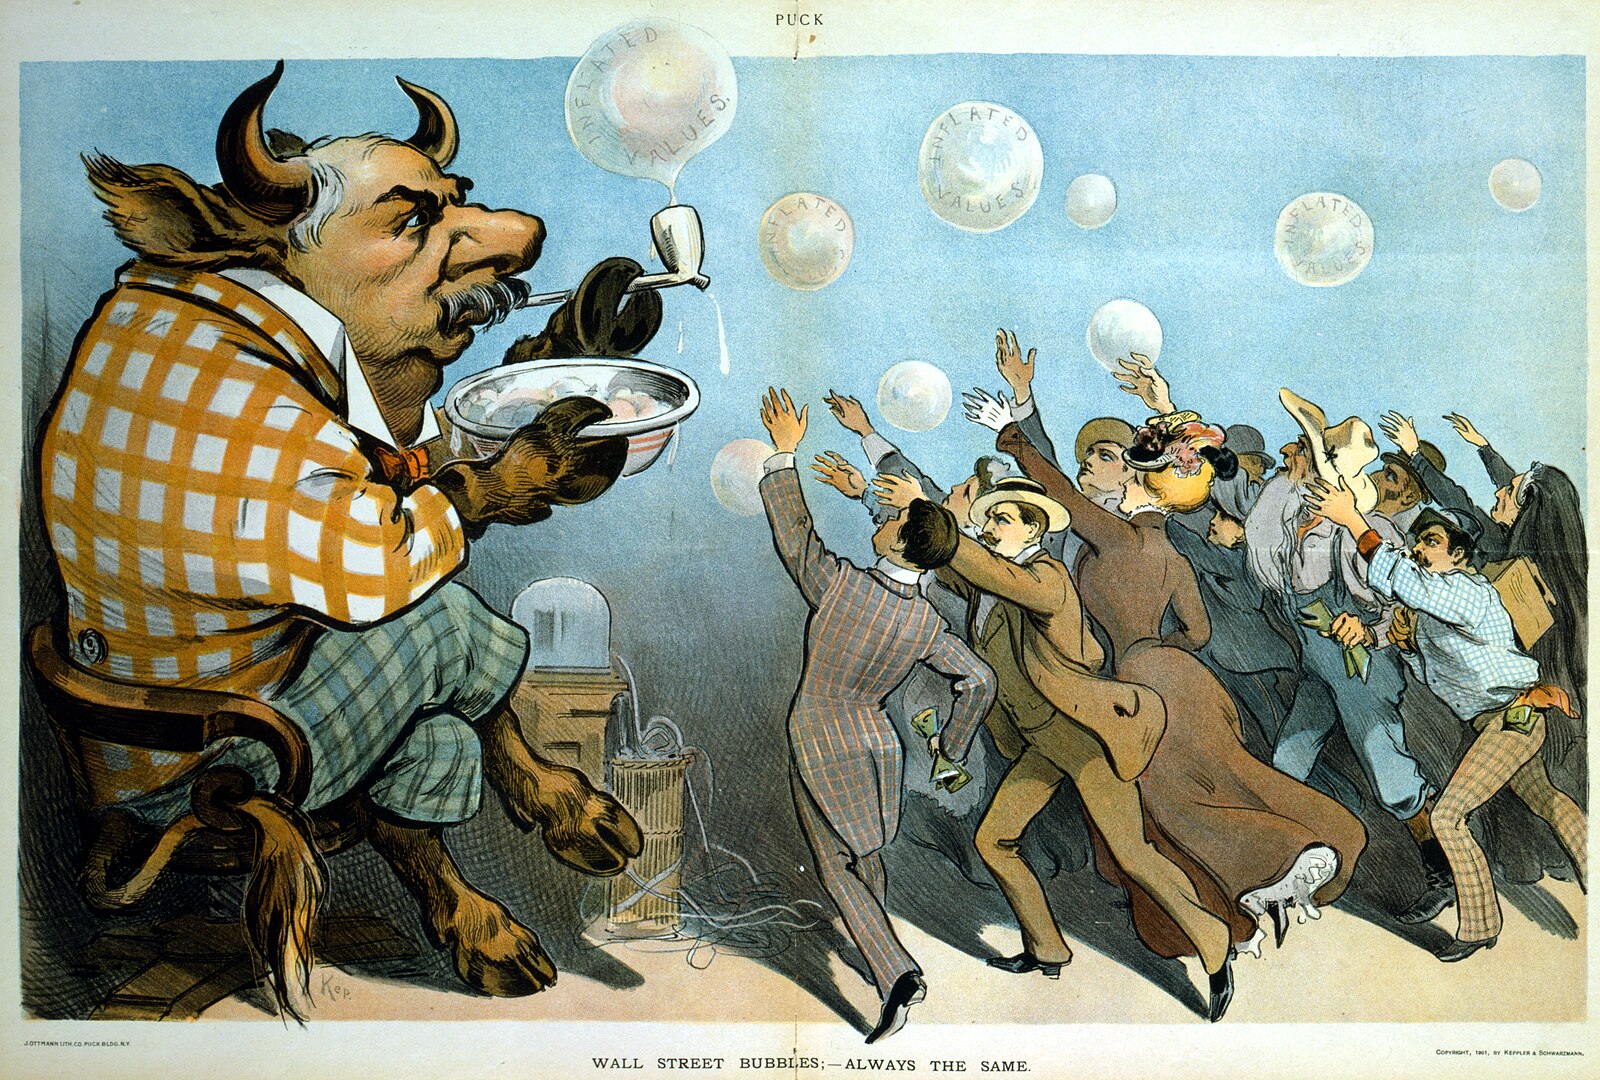
The United States economy is facing several systemic vulnerabilities that are beginning to converge in a nightmare scenario. As the broader economy slows, America’s Gross Domestic Product (GDP) growth is being upheld in large part by massive investments in Artificial Intelligence (AI) technologies.1 However, the boom in AI investment is itself concerning, as valuations and expectations of future growth become increasingly detached from revenue realities.2 Many companies are funding their AI investments through complex, esoteric financial vehicles that have become deeply intertwined with the banking and financial system.3 All of this is occurring alongside a slowing economy, a weakening dollar, and a federal fiscal situation degraded by decades of unproductive borrowing. If the current wave of AI investments is indeed a bubble — as even some business leaders believe — then it has the potential to undermine the entire American economy.4
If this bubble does pop and cascade throughout the economy, policymakers will likely fall back on their traditional model of crisis resolution: privatizing gains while socializing losses by bailing out the big banks and corporations. This approach was cemented during the 2008 Global Financial Crisis, when the federal government committed $250 billion to bailing out banks.5 During the — much more contained — bank failures of 2023, the federal government again improvised a rescue over a weekend — guaranteeing every deposit at Silicon Valley Bank and Signature Bank,6 and handing First Republic Bank to JPMorgan Chase.7 Under this dynamic, the federal government has established an implicit promise to corporations and financial institutions that it will use taxpayer dollars to rescue them from the consequences of their own decisions.
The United States cannot afford another bailout. For decades, the United States has squandered its unique fiscal advantage on corporate rescues, wars of choice, and tax cuts that produced no lasting productive capacity. The well is not infinite. The dollar fell nearly 11% in the first half of 2025;8 demand at some Treasury auctions is softening;9 and the world's patience with American fiscal irresponsibility is wearing thin. The borrowing capacity we have left must be preserved for genuine public investment — infrastructure, industrial policy, climate adaptation — not for rescuing speculators from the consequences of their bets.
The AI sector is approaching a potential correction. If the bubble bursts, it won't stay contained — any losses will cascade into the banking system, triggering insolvencies and mass layoffs in a self-reinforcing spiral. The need for a new framework for how to deal with these crises has never been more urgent.
This report proposes a new framework for managing future financial crises called the Won't Get Fooled Again Act (WGFAA). The WGFAA is designed to update the mechanisms of financial crisis resolution in two ways.
First, it mandates that failed banks and failed systemically important technology companies be converted into mission-driven institutions with no shareholders rather than bailed out, sold to larger rivals, or liquidated. A firm kept alive with emergency federal support is treated as having failed, so a rescue cannot be used to avoid a conversion. The process of converting failed institutions will be funded by industry levies rather than taxpayer dollars, with a Treasury credit line — repaid from those same levies — to cover the early years before the funds have built up.
Second, it expands the definition of systemic importance to encompass the flow of computation, data, and intelligence. Just as the collapse of a major bank threatens the credit lifeline of the real economy, the disorderly failure of a major AI provider or compute provider threatens the digital infrastructure upon which national security, economic competitiveness, and public services increasingly rely. We call these institutions "Systemically Important Technology Institutions" (SITIs).
The framework applies separately to banking and technology. Failed banks of every size become community-focused institutions with no shareholders, owned by their depositors, by their state or city, or, for the largest, by the public, modeled on Germany's Sparkassen system10 and the Bank of North Dakota.11 Failed AI providers become public research utilities, ensuring that critical computational infrastructure remains operational and that valuable intellectual property doesn't flow to foreign adversaries or domestic monopolists in a fire sale.
Crucially, this proposal rejects purchasing equity at bubble prices. It mandates a strict Asset-Based Valuation Standard for any government acquisition, ensuring taxpayers pay only for tangible infrastructure and proven intellectual property — not speculative goodwill or inflated growth projections. Speculators are wiped out while the public gets lasting assets.
The same discipline applies to lenders. The banks, private credit funds, and bondholders who financed the bubble are paid only what their collateral is actually worth on the day of failure — not what they lent against it. Workers, small suppliers, customers, and local governments are paid ahead of the banks and funds, by statute. Pensioners whose savings were steered into these loans are protected through a separate, industry-funded Pension Protection Facility rather than by bailing out the lenders who hold their money.
Finally, the WGFAA closes the back door through which a crash would otherwise make the largest technology companies even larger. It creates a light federal registry and license for large clusters of advanced AI chips, bars any company that already controls more than 5% of the nation's AI computing capacity from buying distressed chips and data centers, and gives the public the first option to acquire them. And whether or not a crash ever comes, a fee paid by the industry funds Community Innovation Hubs — free places to work, learn, and start a business — in every congressional district in the country.
The WGFAA demonstrates that converting failed institutions into public utilities is not merely an ideological preference but a strategic and fiscal necessity — the only path that prevents further concentration of power, preserves America's borrowing capacity for productive investment, and ensures that the transformative power of AI serves the broad American public.
This document describes the Act as it should be passed: in advance, before anything fails. A companion version, the Emergency Version, sets out how the same plan would work if Congress waits until the crash has already begun. That path is harder, more painful, and more expensive, but it exists. Section 12 lists the differences between the two.
1. Dual Bubbles and the Threat to the American Economy
1.1. Convergence of Financial and Technological Fragility
To understand the necessity of the Won't Get Fooled Again Act, one must first dissect the intricate mechanics of the current economic environment. We are witnessing a symbiotic fragility where the banking sector's health is increasingly predicated on the continued inflation of AI asset values, while the AI sector's liquidity is dependent on a banking system exposed to its high-risk debt.
1.1.1. The AI Valuation Paradox: Capital Expenditure vs. Revenue Reality
The current trajectory of the artificial intelligence sector exhibits the classic hallmarks of a speculative mania, distinct in its capital intensity and reliance on projected rather than realized utility. While the technological promise of generative AI is substantial, the financial valuations of companies in this sector may have detached from fundamental economic metrics, creating a "Capex-Revenue Gap" that threatens to destabilize the broader market.12
1.1.2. The "Round-Tripping" Revenue Mirage
A significant portion of the forward revenue of AI companies is arguably artificial, driven by a phenomenon known as "round-tripping" or circular revenue generation.13 The interconnections are dizzying: OpenAI holds warrants to buy up to a 10% stake in AMD;14 Nvidia is investing $30 billion in OpenAI;15 Microsoft is a major shareholder in OpenAI but also a major customer of CoreWeave,16 in which Nvidia holds a significant equity stake;17 and Microsoft accounted for almost 20% of Nvidia's revenue in fiscal 2024, by one UBS estimate.18
Major cloud providers and tech giants invest billions in AI startups, often with the stipulation that the startup spends that capital on the investor's own cloud computing services.19 This creates a "trillion-dollar loop" where investment and purchase commitments on one side become "revenue" on the other, inflating sales figures without representing organic end-user demand. The up to $100 billion Nvidia-OpenAI deal proposed in 2025 exemplifies this structure: Nvidia would pump capital into OpenAI to bankroll data centers, and OpenAI would fill those facilities with Nvidia's chips.20 Nvidia is essentially subsidizing one of its biggest customers, artificially inflating actual demand for AI.
The absurdity of current valuations is captured by recent funding rounds. Thinking Machines, an AI startup helmed by former OpenAI executive Mira Murati, raised the largest seed round in history:21 $2 billion in funding at a $12 billion valuation, closed in July 2025.22 The company has refused to tell investors what it is even trying to build.23 "It was the most absurd pitch meeting," one investor reported. "She was like, 'So we're doing an AI company with the best AI people, but we can't answer any questions.'"24
1.1.3. The Divergence of Investment and Return
Further evidence of the AI market’s core instability can be found in the widening disparity between capital expenditure and realized revenue. Major technology firms and venture-backed startups are investing hundreds of billions of dollars in NVIDIA GPUs, specialized data centers, and energy infrastructure.25 AI-related capital expenditures have, by some estimates, surpassed the U.S. consumer as a primary driver of economic growth,26 adding 1.1 percentage points to GDP growth in the first half of 2025.27 However, the revenue generation from these investments remains dangerously low.
In the first quarter of 2025 alone, global AI startups raised $74 billion, representing a massive concentration of venture capital into a single sector.28 Pitchbook reports that nearly two-thirds of U.S. venture deal value went to AI and Machine Learning startups in the first half of 2025, up from roughly a third in 2023.29 This influx of capital has driven valuations to unsustainable levels, with the median revenue multiple in AI fundraising rounds standing at approximately 30x,30 and many startups valued at 50x to 100x their revenue.31
Despite these massive capital inflows, the profitability remains elusive. OpenAI's ChatGPT, by far the most successful generative AI product to date,32 requires enormous and expensive computing power to run.33 In the first half of 2025, OpenAI reported a net loss of $13.5 billion.34 The flagship product of the AI revolution is bleeding money at a rate of some $27 billion a year.
The continuing investor confidence in the face of these losses suggests that current valuation models are pricing in future popularity and productivity gains of AI tools. However, these gains have been slow to arrive, even in firms that have embraced the new technology. Research from MIT has found that a staggering 95% of organizations attempting to incorporate generative AI into business operations are getting zero measurable return on their investment.35 The results cast doubt on whether the wide array of corporate AI customers the markets expect will actually materialize.
Furthermore, the sector faces the challenge of diminishing returns on model performance relative to cost. The cost of training frontier models is growing exponentially — GPT-4 reportedly cost roughly $78 million to train,36 while successors and competitors are expected to cost a billion dollars or more.37 However, the marginal utility improvements for average users are diminishing, creating a "performance plateau." Users are not willing to pay exponentially higher prices for incrementally better chatbots, yet the infrastructure costs to serve them continue to rise.
An increasing number of market experts have begun warning of the growing instability and uncertain future of the AI sector. Bain & Co.'s annual global technology report says the AI industry will need $2 trillion in new annual revenue by 2030 to continue at its current rate.38 Analyzing similar data, a recent Deutsche Bank report to clients declared such levels of investment as "highly unlikely."39 Echoing these concerns, a Bank of England report from October warns that the market could experience a "sharp correction" due to overvaluation.40
1.1.4. The Hardware Choke and Inventory Glut
One significant factor driving up both AI computing costs and company valuations is the scarcity of computer chips.41 NVIDIA's market capitalization exceeded $5 trillion on 29 October 2025,42 rising higher than the GDP of every country except the US and China.43 A significant percentage of its data center revenue is tied to a small handful of hyperscalers and AI cloud providers.44 As discussed above, this concentration risk is exacerbated by vendor financing, where chip manufacturers or cloud providers invest in the very startups that are buying their chips, creating a circular revenue model that inflates reported sales without generating net new economic value.
These tactics create significant potential for an inventory glut. As companies race to build GPU clusters to avoid being left behind, they risk creating massive overcapacity. If the demand for AI services does not match the massive supply of compute coming online, the rental price of GPUs could crash. In addition to being dire for giants like NVIDIA, this would destroy the business models of "compute-as-a-service" startups, as their projected margins rely in part on continued scarcity pricing of chips.
1.2. The Banking Sector's "Hidden" Exposure
The risks and inherent instability discussed above are all the more troubling because of the ways our entire financial system is becoming increasingly entwined with the fate of the AI market. The banking sector's exposure to the risks of the AI bubble is multifaceted and opaque, extending far beyond direct commercial loans. It includes exposure to the "shadow banking" system, complex off-balance-sheet arrangements that echo the financial engineering of past crises, and venture debt.
1.2.1. The Shadow Banking Transmission Mechanism
A growing share of the lending to risky AI ventures has gone to the "shadow banking" or private credit sector,45 which by some estimates is now worth $3.5 trillion in assets.46 Unlike traditional banks, which use customer deposits to back their loans, private credit firms raise the capital for their loans from private investors such as pensions, wealth funds, or high-net-worth individuals. Free of the regulations imposed on traditional banks after the 2008 financial crisis, these companies are able to provide higher-risk loans to companies, including large corporations.47 In theory, private investors bear the losses if these loans default, insulating the wider economy from the kind of market volatility that can kick off a financial crisis. But the reality is more interconnected. Traditional banks lend heavily to these private credit funds, creating a chain of exposure that is difficult to quantify but carries grave risks for the American public.48
If AI startups begin to default on their private credit obligations — a likely scenario given high "burn rates" and lack of profitability — the losses will flow back to the balance sheets of the major banks that provide leverage to private credit funds.
Recent failures in the private credit market outside the technology sector, such as the collapse of Tricolor Holdings, have already revealed the opacity and weak underwriting standards that characterize this sector.49 Tricolor, which both sold used cars and provided subprime auto loans to borrowers with poor or no credit, declared bankruptcy in September 2025.50 Despite being a private credit institution, the collapse led to substantial losses for their lenders in the traditional banking sector, such as JP Morgan Chase and Fifth Third Bank.51 In response, JPMorgan CEO Jamie Dimon has warned that more "cockroaches" will likely emerge.52 The contagion risk is significant: if collective wisdom determines that private credit dynamics pose a systemic threat, a self-fulfilling liquidity crisis could ensue, freezing credit markets exactly as they did in 2008.
1.2.2. Cooking the Books
Adding to the alarm is the notable off-balance-sheet financial engineering at the largest AI companies. Major technology firms are using complex accounting structures to obscure the true scale of their AI infrastructure bets.53 In one representative deal, Blue Owl Capital joined a $27 billion joint venture to build a data center.54 Meta's lease payments and a 16-year residual value guarantee stand behind the debt, yet the $27 billion bond, raised in October 2025 by the Meta–Blue Owl joint venture (Beignet Investor LLC) rather than borrowed by Meta, never shows up on Meta's balance sheet.55 If the AI bubble bursts and the data center goes dark, Meta could be on the hook for a multi-billion-dollar payment. Some analysts have flagged the structure of the deal as misleading, as it effectively conceals massive debts and allows Meta to project a false image of financial health.56 The financial maneuvering implies a deep fragility beneath the surface of big AI, casting doubt on whether the industry's explosive growth is supported by actual economic reality.
1.2.3. Venture Debt and the Collateral Crisis
Even the more straightforward financing structures carry grave risks for the wider economy. AI startups have increasingly turned to venture debt. AI startups took nearly one in four venture debt dollars in 2024, and their share climbed past a third in the first half of 2025.57 This debt is often secured not by cash flows (which are minimal), but by the assets of the company — for AI infrastructure startups especially, their high-value GPU hardware.58
This creates a dangerous collateral vulnerability. In a market crash, the value of these GPUs — much of the collateral backing billions in loans — would plummet due to the aforementioned inventory glut. Banks and debt funds would find themselves holding depreciating hardware assets rather than recoverable capital. The liquidation of these assets to recover losses would further depress hardware prices, triggering a deflationary spiral in the tech hardware market that could make additional firms holding similar collateral insolvent.
1.2.4. Data Center Finance and Energy Exposure
Even if investor dollars continue to flow, many experts warn that energy needs will likely constrain the sector’s growth.59 The physical infrastructure of AI — hyperscale data centers — is often financed through complex project finance structures involving large syndicates of banks.60 Massive loans for projects like Oracle's "Stargate" involve dozens of financial institutions.61
However, the energy bottleneck threatens the viability of these projects. The immense power requirements of data centers are colliding with grid limitations, leading to utility rate hikes and in some cases the cancellation of other energy projects to feed AI demand.62 Major cloud computing providers like Oracle, despite elite clientele and billions in contracts, are struggling to secure the energy infrastructure they need to complete major projects.63
Physical power shortages or consumer backlash could force the abandonment of half-finished infrastructure projects. A data center that cannot get a power connection is a distressed asset with zero revenue potential. Banks holding the construction loans for these stranded assets would face significant write-downs, mirroring the commercial real estate crisis but focused on digital infrastructure.
Communities are beginning to resist. In Prince William County, Virginia, more than a hundred owners of rural land and homes contracted to sell to data center developers,64 and their neighbors went to court to stop the project.65 This is the beginning of a NIMBY phenomenon that could further delay or halt infrastructure build-out.
1.2.5. Who Is Lending, Who Is Paying, and What Backs It All
No single source publishes a clean map of the money behind the build-out, and any account of it has to be assembled from company filings, deal announcements, and analyst estimates. What follows is New Consensus's best reading of that evidence. The figures are indicative, not audited.
Who is lending. Morgan Stanley's estimate is that of the roughly $1.5 trillion the build-out must raise from outside investors through 2028, about half will come from private credit funds and asset-based lenders, something over a tenth from investment grade technology corporate bond issuance, a tenth from securitizations of data center properties and leases, and the rest from a mix of equity, sovereign funds, and banks.66 Banks show up less as direct lenders than as the lenders to the lenders. American banks had about $1.3 trillion of loans outstanding to non-bank financial firms as of the third quarter of 2025,67 with an estimated nearly $1 trillion more committed but undrawn as of early 2025,68 and the Federal Reserve counts $2.6 trillion in bank credit commitments to such firms in the fourth quarter of 2025.69 Only a fraction of that is to private credit funds — the Fed's own count of large banks' credit lines to private credit vehicles is around $95 billion — but that is precisely the channel through which a private credit loss reaches a bank.70 Behind the funds stand the ultimate investors: pension funds, life insurers, sovereign wealth funds, endowments, and wealthy individuals. Insurers alone held some $277 billion of collateralized loan obligations, measured at book/adjusted carrying value, at the end of 2024, 82% of it at life insurers.71
What backs the loans. Bonds issued by the largest technology companies are unsecured,72 and they do not need to be: those companies fund most of their spending from profits.73 Nearly everything else is secured by something. Loans to the GPU-rental companies are often secured by the chips, by the customer contracts, and by the shell companies that hold both.74 Data center loans are secured by the land and buildings and by the tenant's lease. Securitizations are secured by pools of leases and equipment. One tracker counts about $58 billion issued across 36 deals secured directly by GPUs, a measure of issuance rather than outstanding balances.75 The practical consequence is that in a crash the lenders who matter are secured lenders, and the question is not whether they hold collateral but what it will be worth.
Who is ultimately paying. The collateral behind many of the biggest loans includes a customer's promise to pay for computing over several years. Whether that promise is worth anything depends on who made it. A contract with a profitable giant such as Microsoft or Meta holds its value so long as service continues. A contract with an AI laboratory holds its value only so long as the laboratory can keep raising money, because none of them is yet reliably profitable.76 No public source we found gives the split, but the reported contracts suggest a rough picture. On the side of the giants: Meta's commitments to CoreWeave (about $35 billion contracted) and to Nebius (up to about $27 billion over five years, announced in March 2026),77 and Microsoft's contracts with CoreWeave and Nebius.78 On the side of the laboratories: OpenAI's roughly $300 billion contract with Oracle, covering roughly five years starting in 2027,79 and Bank of America estimates OpenAI accounts for more than half80 of the $638 billion backlog Oracle reported for May 31, 2026;81 OpenAI's commitments to CoreWeave;82 Anthropic's reported $35 billion arrangement with Lambda83 and 20-year lease with TeraWulf, expected to generate ~$19 billion of contracted revenue for TeraWulf over the initial lease term;84 and the data centers being built for Oracle to serve OpenAI.85 Tallied that way, something like two-thirds of the contracted dollars behind the specialist providers rest on a laboratory's ability to pay, and one-third on a giant's — and the laboratory-backed share appears concentrated in a handful of firms, which are the ones most likely to fail. The chips themselves are concentrated too. By one independent estimate, five American technology giants — Amazon, Google, Meta, Microsoft, and Oracle — owned 71% of the world's AI computing capacity at the end of 2025, up from 63% in early 2024,86 with Google alone holding about a quarter of it, most of that in chips of its own design.87 We found no comparable count for the United States alone, or for who operates the chips as opposed to who owns them — which is one reason the Act creates a registry (Section 5.4). The picture is complicated by the fact that Microsoft reportedly rents capacity partly to serve OpenAI,88 so that if OpenAI stopped paying, Microsoft would still owe its providers and would take the loss itself; and by reports that Google stands behind some of Anthropic's leases.89 The estimate could easily be off by a good deal. What it shows is where the weight sits.
1.3. System-Wide Risks to the Financial System
As discussed above, these warning signs are all the more troubling because of the central role AI is playing in fueling the growth of the US economy.90 In keeping with the consolidated nature of the tech industry, compute is dominated by three major cloud providers (Amazon, Microsoft, Google), which together hold 57% of worldwide hyperscale capacity, and a handful of foundational model developers.91 This creates "single-point-of-failure" risks for the entire economy, including the financial system itself.
Financial institutions increasingly rely on AI for critical operations: fraud detection, credit underwriting, algorithmic trading, customer service, and risk modeling.92 A failure, bankruptcy, or service disruption of a major AI provider could paralyze banking operations, creating a direct channel for contagion from the tech sector to the financial sector.
Furthermore, the equity concentration of the "Magnificent Seven" tech company stocks (Apple, Microsoft, Amazon, Alphabet, Meta, Nvidia, and Tesla) in pension funds and institutional portfolios means that a bursting of the AI bubble would cause a massive negative wealth effect.93 In 2026, 30% of the S&P 500 was held by five companies94 — among the highest concentrations in decades.95 AI-related enterprises accounted for roughly 75% of gains in the S&P 500 since ChatGPT launched in late 2022.96 A crash would erode the capital base of the financial system and damage consumer confidence, potentially triggering a recession that would cycle back to cause defaults on traditional bank loans. This is not diversification; it is concentration risk masquerading as a market rally.
1.4. The Labor Displacement Accelerant
The looming bursting of the AI bubble will not end AI-driven labor displacement — it will accelerate it. This counterintuitive dynamic creates a vicious cycle that compounds the economic damage of a financial correction.
The current wave of AI-enabled layoffs is already staggering. In October 2025 alone, according to Challenger, Gray & Christmas, employers announced 153,074 job cuts — the highest October total in 22 years and the highest single month in the fourth quarter since 2008.97 Announced job cuts through November 2025 had surpassed 1.1 million, the most since the pandemic.98 Technology and warehousing were the hardest hit, with tech companies announcing 33,281 job cuts in October (nearly six times September's figure) and warehousing companies announcing 47,878 cuts (up from 984 in September, an increase of about 4,770%).99
According to the World Economic Forum's 2025 Future of Jobs report, 41% of employers worldwide intend to reduce their workforce in the next five years due to AI driven skills obsolescence.100 Anthropic CEO Dario Amodei has predicted that generative AI could wipe out up to half of entry-level white-collar jobs in the next one to five years.101 Klarna has shrunk its headcount by nearly half since 2022, in part because of AI.102 Salesforce cut 4,000 customer support roles,103 stating that AI handles about half of customer conversations.104 Duolingo has said it will gradually stop using contractors for work that AI can handle.105
Here is the critical dynamic: during the current boom, companies have not tried very hard to realize AI productivity gains. Flush with cheap capital and optimistic projections, firms have been content to experiment with AI while maintaining existing headcount.
A financial crash changes this calculus entirely. Under severe cost pressure, companies will finally do the hard work of restructuring operations around AI capabilities. They will discover productivity gains that seemed elusive during the boom — not because the technology has improved, but because desperation focuses the mind. The layoffs we have seen so far are a preview; a crash would trigger a tsunami.
This creates a doom loop:
AI bubble bursts → asset values collapse, credit tightens → Companies face cost pressure → aggressively implement AI to cut headcount → Mass layoffs → consumer spending falls, demand destruction → Recession deepens → more companies face cost pressure → Return to step 2
2. The Fiscal Constraint
2.1. Preserving America's Borrowing Capacity
The Won't Get Fooled Again Act is not merely good policy; it is fiscal necessity. America's ability to borrow — the foundation of its economic flexibility and geopolitical power — is increasingly at risk from decades of unproductive spending.106 We cannot afford another multi-trillion-dollar bailout, and attempting one could trigger a crisis of confidence in the dollar itself.
2.1.1. The True Cost of "Free" Bailouts
For decades, a bipartisan consensus has held that large-scale government borrowing is justified when invested in productive capacity. This view, associated with economists in the Keynesian tradition, correctly recognizes that a sovereign nation issuing debt in its own currency faces different constraints than a household or business. When borrowed funds flow into infrastructure, education, research, and industry, they generate returns that exceed the cost of servicing the debt.
The tragedy of American fiscal policy is that we have borrowed like believers in public investment while spending like opponents of it.
Between fiscal 2000 and fiscal 2024, the United States added approximately $30 trillion to its national debt.107 What do we have to show for it?
$4-8 trillion on the post-9/11 wars, including Iraq and Afghanistan108 that destabilized the Middle East, created ISIS,109 and produced no lasting strategic benefit. About $1.5 trillion in tax cuts over FY2018–FY2027 (2017 Tax Cuts and Jobs Act)110 that primarily benefited corporations and the wealthy,111 with no clearly demonstrated increase in productive investment.112 $500 billion in direct bailout costs from the 2008 financial crisis,113 plus over $1 trillion outstanding in peak Federal Reserve emergency lending.114 Vast sums in improvised guarantees during the 2023 banking turmoil — coverage for which no bank had ever paid a premium, extended over a weekend.115 Ongoing annual deficits reaching 5.8% of GDP in the CBO FY2026 baseline and projected to rise, with no plan for productive deployment.116
What we did not build:
- A modern passenger rail network (China built 31,317 miles of high-speed rail;117 we built zero miles of dedicated high-speed line).118
- A resilient electrical grid capable of supporting clean energy and advanced manufacturing.
- Universal high-speed broadband connecting rural and urban America.
- Domestic leading-edge semiconductor capacity at scale (until the recent, inadequate CHIPS Act).
- Public AI research infrastructure ensuring American competitiveness for decades.
- Affordable housing at scale addressing the affordability crisis.
Instead, we have been drawing down our most valuable national asset — the world's trust in American debt — to finance empty consumption, crisis management, and the socialization of private losses.
2.1.2. The Dollar's Eroding Foundation
While this bipartisan consensus still largely controls Washington, the economic warning signs are now impossible to ignore.
The dollar index fell 10.8% in the first half of 2025119 — the worst first half since 1973.120 Over the year as a whole it was down nearly 10% against a basket of major currencies.121 The euro rose 13% against the dollar in 2025 as investors focused on growth risks inside the United States.122
Interest payments on federal debt now exceed the entire defense budget,123 and are projected to rise to about 26% of federal revenue.124 The Congressional Budget Office projects that interest costs reach $1 trillion annually in 2026.125 It's a spending trend that has persisted over several different presidential administrations,126 leading Harvard economist Kenneth Rogoff to recently remark, "both parties in the United States seem to think that debt is a free lunch."127
Foreign demand for Treasuries — once insatiable — is softening.128 The share of U.S. debt held by the public owned by foreigners has fallen from about half to around a third today.129 Central banks worried about devaluation of their dollar assets are buying gold at a historically rapid pace.130 Moody's stripped the U.S. government of its top credit rating in 2025.131
As a Chatham House analysis concluded: "If the international monetary system cannot rely on the dollar's full convertibility, or its availability in a crisis, it is entering unknown territory."132
This is not an argument for austerity. It is an argument for prioritization. America still possesses the capacity to borrow for productive investment — but only if we stop squandering that capacity on preventable crises and speculator rescues.
2.1.3. The WGFAA as Fiscal Insurance
The Won't Get Fooled Again Act is designed to ensure that the next financial crisis — which the convergence of AI speculation and banking fragility makes nearly inevitable — does not require another multi-trillion-dollar emergency intervention.
Unlike previous crisis responses:
The WGFAA is pre-funded by the industries creating the risk. The Digital Stability Fund and the Public Bank Capitalization Fund, financed by compute taxes and G-SIB surcharges, ensure that resolution costs are borne by speculators, not taxpayers. The financial sector pays for bank resolutions; the tech sector pays for AI company resolutions. This is not a tax on productive activity; it is an insurance premium on speculation.
The WGFAA converts crisis into asset. Rather than pouring public money into a hole to restore the status quo ante — leaving us with the same fragile system that produced the crisis — the conversion protocol transforms failed institutions into permanent public infrastructure. Banks that serve communities rather than shareholders. Research institutes that advance safety rather than quarterly earnings. Compute utilities that democratize access rather than concentrate power.
The WGFAA preserves fiscal space for genuine public investment. Every dollar we don't spend bailing out AI speculation is a dollar available for grid modernization, semiconductor independence, climate adaptation, housing, healthcare, and the public services that build shared prosperity. We cannot afford to do both; we must choose.
The choice before us is not between intervention and non-intervention. A crisis is coming; some form of public response will be necessary. The choice is between:
An intervention that costs the public everything and returns nothing — trillions in bailout funds flowing to speculators, the same fragile system restored, our borrowing capacity further depleted.
An intervention that costs the public nothing and returns lasting assets — industry-funded resolutions that convert failed speculation into permanent public infrastructure.
We argue for the second approach, and the WGFAA is the guide.
3. The Failure of the Status Quo
3.1. Why "No Bailout" Is a Myth
The response to the banking turmoil of 2023 has created a dangerous moral hazard that must be addressed before the next crisis strikes. The rhetoric of market discipline has been exposed as hollow; the reality is a system that protects the connected while concentrating risk in ever-larger institutions.
3.1.1. The Hollow Rhetoric of 2023
The failures of Silicon Valley Bank, Signature Bank, and First Republic Bank in 2023 exposed the emptiness of the "no bailout" rhetoric espoused by political leaders.133 Officially, deposit insurance stops at $250,000 per depositor, per insured bank, per ownership category.134 In practice, when Silicon Valley Bank failed — with some 94% of its deposits at the end of 2022 above that limit135 — regulators guaranteed every dollar over a weekend.136
The problem was not that depositors were protected. It was how. The guarantee was improvised, it was not paid for in advance — no bank had ever paid a premium for that coverage — and it was discretionary.137 Nobody knows whether the next failed bank's depositors will receive the same treatment. That uncertainty is not neutral. Everyone understands that the government will never let depositors at JPMorgan Chase or Bank of America lose money, whatever the law says. Depositors at every other bank have to guess.
The result is a system that rescues the megabanks by accident. The moment a mid-size bank wobbles, large depositors everywhere move their money to the handful of banks they believe are too big to fail. In the week ended March 15, 2023, just after Silicon Valley Bank failed, about $120 billion in deposits left the country's smaller banks, by the Fed's initial estimate (later revised to about $196 billion),138 while the 25 largest banks gained about $67 billion.139 A panic that ought to test every bank's soundness instead hands the biggest banks a flood of cheap funding, whatever the condition of their own balance sheets, and drains the smaller banks that compete with them. A megabank that ought to fail can be kept alive by everyone else's fear. A sound community bank can be killed by it.
This is not capitalism; it is a system of privatized gains and socialized losses in which the implicit guarantee is handed out by size. It corrodes both economic efficiency and democratic legitimacy, and — as the next section shows — it feeds directly into consolidation.
3.1.2. The Consolidation Trap
The current resolution regime for failed banks exacerbates the "Too Big to Fail" problem rather than solving it. The FDIC's standard operating procedure is to sell the assets of a failed bank to a healthy institution.140 The bulk of First Republic Bank's assets were sold to JPMorgan Chase, already the largest bank in the United States.141
This approach creates a paradox: to solve a temporary liquidity crisis, regulators permanently increase the concentration of the banking sector. Crises tend to leave us with fewer, larger banks — institutions that are even more "too big to fail" than their predecessors. This reduces competition, increases systemic risk posed by the surviving mega-banks, and leaves communities with fewer options for credit and financial services.
As the banking sector consolidates, it becomes less responsive to local economic needs and more focused on global capital markets and speculative activities. The community bank that once financed the local hardware store can be absorbed into a behemoth more interested in derivatives trading than small business lending.
The WGFAA breaks this cycle. By converting failed banks into public benefit institutions rather than selling them to competitors, we preserve competition, maintain local credit access, and stop feeding the consolidation machine.
3.1.3. The Inadequacy of Bankruptcy for AI
Just as our current financial regulations have only compounded issues like consolidation and reckless speculation, applying traditional bankruptcy procedures to failed AI companies presents unique risks that current laws are ill-equipped to handle.
IP Flight and National Security Risks: In a standard bankruptcy liquidation, assets are sold to the highest bidder. For a failed AI provider, key assets are the "model weights" — the numerical parameters that define the AI's intelligence. If these weights are sold on the open market to satisfy creditors, they could be acquired by foreign adversaries or non-state actors, posing severe national security risks. A Chinese tech giant or a sovereign wealth fund could acquire capabilities that will cost billions to develop by 2027 for pennies on the dollar in a fire sale.
Spreading Sensitive Data: In addition to the underlying technology, many AI companies have access to vast amounts of personal information on their users, with some LLMs now specifically trained for healthcare and financial advice.142 In the event of a company failure, this intimate data could be auctioned off to data brokers, advertisers, or surveillance firms, effectively paying back creditors with customer privacy.
Service Disruption: A Chapter 7 liquidation involves ceasing operations. As discussed earlier, for an AI company providing critical infrastructure to hospitals, energy grids, financial systems, or government agencies, an abrupt shutdown would be catastrophic. Millions of API calls per day would simply stop working. The "wind-down" of such a company requires continuity of service that a liquidation trustee focused on creditor recovery is not incentivized or equipped to provide.
Loss of Public Investment: The immense public investment in these technologies — through tax breaks and other subsidies, and decades of university research — would be lost if the assets were simply scrapped or sold to a private monopoly. The public funded the basic research that made these technologies possible; the public should not lose everything when a private venture built on that research fails.143
Concentration of Private Power: Even setting aside foreign acquisition, domestic consolidation poses risks. If a failed AI provider's assets are acquired by one of the surviving hyperscalers, we simply exchange one form of fragility for another — further concentrating the market and increasing the systemic importance of the acquirer. Nor is the danger confined to the failure of one giant. The more likely fire sale is dozens of mid-size GPU-rental companies and data center operators failing in the same season — none of them individually "systemic" — with their hardware bought for pennies on the dollar by the three or four companies that already dominate cloud computing.
Lender Foreclosure: Many of the chips at risk are already pledged.144 The loans that financed the build-out are secured by the customer contracts — lenders have generally refused to treat the chips alone as enough security145 — and by the GPUs and the shell companies that hold them;146 in some structures a finance vehicle owns the chips outright and leases them to the operator.147 When a borrower defaults, the lenders move on both: they claim the contract revenue and they seize the hardware and sell it to whoever pays most, without needing a court's approval.148 The race in a crash is as much a fight over who collects the contracts as over who gets the chips (Section 1.2.5), and a resolution regime that cannot stop either will arrive to find nothing left to resolve.
The WGFAA provides an alternative path: conversion to public ownership that maintains service continuity, preserves national security and personal privacy, retains the value of public investment, and prevents further market concentration.
4. The Banking Solution
4.1. Breaking the Cycle of Bailouts and Consolidation
The chronic instability of the national U.S. banking sector is not an inevitability. In fact, it is the result of decades of short-sighted economic policy. Other industrialized nations, even individual US states, maintain banking systems with significantly lower failure rates.149 The WGFAA draws on these successful models to propose a fundamental restructuring of how America handles failed banks.
Every failed bank that is still a functioning bank is converted, whatever its size. A small town's bank matters as much to the people who depend on it as a giant bank matters to the country. A rule that converted only the largest banks would leave every other failed bank to be sold in the usual way, usually to a bigger bank, and would treat the giants' customers better than everyone else's.150 Under the WGFAA, size decides only who owns the converted bank (Section 4.1.4). It never decides whether the bank is converted.
What counts as a functioning bank is written into the statute. A failed bank is converted unless the FDIC finds, in writing, that one of three things is true: it has no real base of customer deposits, because its funding was mostly brokered deposits or other hot money; it has no real business of lending to households and firms; or its failure was driven mainly by fraud, leaving little sound business to keep. The FDIC applies the test one bank at a time, but conversion is the default, and every finding that a bank should not be converted is published with its reasons. When a bank fails the test, its customers' accounts and its sound loans are moved to a nearby Public Benefit Bank, credit union, or community bank. They are never sold to a bank with more than $250 billion in assets. These are plain rules, written down in advance. There is no room for banks to negotiate their way out of the conversion framework.
4.1.1. Better Banking Models: Stability by Design
Germany's Sparkassen (Public Savings Banks): Germany relies on a network of around 337 Sparkassen, or municipal savings banks.151 These are generally public law institutions whose mandate is to serve the local region, not to maximize shareholder profit.152 They are legally restricted from engaging in high-risk speculative trading.153 During the 2008 crisis, while private German banks suffered, the Sparkassen actually increased their lending to small and medium-sized enterprises, acting as a stabilizer for the real economy rather than a vector of contagion.154 This model demonstrates that public banking is not only viable but actively superior at serving the real economy during periods of stress.
Canada's Stability Culture: Canada's banking system is widely regarded as one of the most stable in the world.155 It avoided the worst of the 2008 crisis largely due to a regulatory culture that prioritizes stability over financial innovation.156 Canadian mortgages carry strict origination standards; the risk-taking ethos of American finance is foreign to Canadian banking culture.157 The WGFAA seeks to import this stability by converting failed U.S. banks into institutions that prioritize reliable utility banking over speculative growth.
The Bank of North Dakota (BND): Within the United States, the state-owned Bank of North Dakota offers a powerful precedent. Established in 1919,158 it acts as a "banker's bank," partnering with local community banks to increase lending capacity rather than competing with them.159 In 2024, BND earned a return on average assets of 1.91%160, far above the 1.1% median for U.S. banks rated by S&P Global through the first nine months of 2024,161 while taking none of the speculative risks that periodically blow up Wall Street balance sheets. It exists primarily to serve North Dakota's economy. It has never required a bailout,162 and it returns its profits to the state: $140 million to the general fund for the 2025-27 biennium,163 and $335 million in total returns to the state in 2024,164 directly reducing the tax burden on North Dakota residents. The BND demonstrates that public banking works in America, we simply haven't scaled it.
4.1.2. The Bank Conversion Protocol
Under the WGFAA, when a functioning bank fails, it will not be sold to a larger private bank (increasing consolidation) or bailed out to preserve shareholder value (rewarding speculation). Instead, it will be converted into a Public Benefit Bank. A bank kept alive with emergency federal support is treated the same way: under Section 6.6, taking that support counts as failing.
This requires changing one rule in particular. Current law obliges the FDIC to resolve a failed bank by whatever method costs its insurance fund the least,165 and the cheapest method is usually a sale to another bank.166 That rule is why failed banks keep ending up inside other banks.167 The WGFAA amends it: for every failed bank that passes the test above, conversion is the required resolution, and the cost to the fund is weighed against the public value of the institution that results, not against the highest bid. The Act also repeals the exception that lets a bank already over the nationwide deposit cap buy a failed bank (Section 5.4.5), so that no failed bank's business can be handed to the largest banks by that route.168
The conversion timeline mirrors existing FDIC practice for failed bank resolutions — typically completed over a single weekend.169 On Friday evening, the FDIC assumes receivership. Over the weekend, the charter conversion is executed, an interim board is appointed, and executive leadership transition begins. On Monday morning, branches open under the new Public Benefit Bank charter. Depositors notice nothing; their accounts function normally. The bank keeps its name, its signs, and its brand. The change customers will notice, over time, is in its lending: a shift from shareholder returns to community development. This is not theoretical; the FDIC has executed over 500 bank resolutions since 2008.170
4.1.3. Automatic Charter Conversion to Public Benefit Bank (PBB)
Upon receivership, the failed bank's private charter is revoked. A new charter is issued, designating the entity as a Public Benefit Bank (PBB). Every converted bank is a Public Benefit Bank, whoever owns it (Section 4.1.4): it has no shareholders, it carries the mission set out below, and it is barred from the activities listed below.
Mission Mandate: The new PBB is statutorily required to put its lending to productive use. Its lending portfolio must shift away from speculative asset financing and toward productive lending: small business loans, infrastructure financing, affordable housing, and community development. The extractive logic of shareholder value maximization is replaced by a mandate to serve the communities where the bank operates.
National Banks: The largest converted banks are national institutions, and their mandate is national as well. A bank with customers in every state keeps lending in the communities it serves, and it also puts its size to work on the country's big undertakings: new industries, major infrastructure, and the ambitious ventures that the megabanks passed over because trading paid better.171
Prohibited Activities: The PBB is strictly prohibited from engaging in proprietary trading, derivatives speculation, or financing of other financial intermediaries (shadow banks). It returns to the boring, essential work of banking: taking deposits and making loans to productive enterprises.
Operational Continuity: The bank retains its branches, depositor accounts, and non-executive staff, ensuring no disruption to customers. The teller at your local branch keeps their job; your checking account continues to function; your small business line of credit remains in place. The only change customers perceive is the shift in the bank's long-term mission and the removal of shareholder pressure to maximize short-term profits at the expense of customer welfare.
This is not nationalization in the Venezuelan or Argentine sense — a government seizing profitable enterprises to extract their value. The conversion protocol applies only to failed institutions already in FDIC receivership. The shareholders have already lost; their equity is usually worthless.172 The question is not whether to expropriate private property, but what to do with the wreckage. The current answer — usually sell it to a larger bank, sometimes increasing concentration — serves no one but the acquiring bank's shareholders.173 The WGFAA answer — convert it to public purpose — serves the communities that depend on local credit. Critics who call this "socialism" are defending a system where private failure becomes public bailout but private success remains private profit. That is not capitalism; it is a rigged game.
To be clear: "shareholders wiped out" means existing equity is extinguished — worth zero. The physical branches and loan portfolios become assets of the newly chartered Public Benefit Bank, which also takes on the failed bank's obligations to its depositors. The former shareholders receive nothing because their equity was already worthless at the point of FDIC receivership; the government is not taking assets from them but rather preventing those assets from being sold to a competing mega-bank at fire-sale prices.
What Moves and What Stays Behind: A bank owes money to two very different groups. Depositors are customers; their accounts are the business itself, and they move to the Public Benefit Bank along with the loans and branches that back them. Bondholders, subordinated debt holders, and the creditors of the parent holding company are investors who were paid interest to bear risk. Their claims stay behind in the receivership of the failed bank, alongside the worthless shares, and are paid only from whatever the FDIC recovers. This is broadly how the FDIC already resolves failed banks,174 and federal law already ranks depositors ahead of bondholders.175 The largest banks are in fact required to issue a thick layer of long-term debt whose stated purpose is to absorb losses in a failure.176 The WGFAA simply insists that it be used.
Deposit Coverage: The WGFAA insures all deposits, at every insured bank, explicitly and in advance. Banks pay for the coverage through risk-based premiums. There are four reasons.
First, it ends the accidental rescue of the megabanks. As Section 3.1.1 showed, a limit on insurance does not impose discipline evenly. It sends money fleeing, at the first sign of trouble, from smaller banks to the few that everyone believes the government stands behind. If a megabank is insolvent, it should be found insolvent and converted under this Act — not floated through the crisis on deposits that fled from its sounder competitors. Only when a deposit is equally safe at every bank does a panic stop working as a subsidy to size.
Second, it stops the consolidation that follows. When runs topple mid-size banks, they tend to end the same way: fewer, larger banks.177 Some $7.7 trillion of American deposits at the end of 2022 — 43% of the total — sit above the insurance limit.178 As long as that money is safe only at the largest banks, it will keep migrating to them, crisis after crisis.
Third, a converted bank needs its depositors. The point of conversion is to keep a working bank — its branches, its loans, its customer relationships — in service to its community. A bank that loses half its deposits on the way to conversion is not a functioning piece of public infrastructure; it is a shell. A full guarantee means the deposits stay where they are, and the Public Benefit Bank opens on Monday morning with its funding intact.
Fourth, depositors were never the source of discipline that theory makes them out to be. Silicon Valley Bank's depositors included many sophisticated investors, and they noticed nothing until the day they all ran at once: on March 9, 2023, $42 billion left in a single day,179 with about another $100 billion queued for the next morning.180 A payroll clerk cannot audit a bank's bond portfolio, and should not have to. Under the WGFAA, discipline falls on the people who are paid to bear risk and have the means to judge it: shareholders, who are wiped out; bondholders, who are left behind in the receivership; and executives, whose pay is clawed back.
The familiar objection is that insuring every deposit invites recklessness: a badly run bank could raise unlimited insured funds and gamble with them, as the savings and loans did in the 1980s. The answer is that the guarantee already exists wherever it matters most, and at present it is free. The WGFAA makes it explicit and makes banks pay for it. Premiums on the newly covered deposits rise with a bank's risk and with its size, so the largest banks — which have enjoyed the implicit guarantee without charge — pay the most. And a bank that gambles with insured money now faces a consequence its owners cannot escape: not a bailout, not a sale to a friendly rival, but conversion. Full insurance does remove one crude alarm. A run is how a failing bank has often been exposed, and without runs a bank that is quietly insolvent can stay open longer, as the savings and loans did. Regulators therefore carry the whole burden of closing bad banks early, and the Act gives them both the duty and a ready destination: a bank whose capital falls below the existing prompt-corrective-action floor is placed in receivership and, if it is a functioning bank, converted.
There is precedent. From 2010 through 2012, Congress insured noninterest-bearing transaction accounts without limit.181 After the 2023 failures the FDIC itself studied unlimited coverage and concluded that, of the options it considered, it offers the clearest solution to bank runs and the greatest benefit to financial stability, while warning of its cost to the insurance fund and its effect on risk-taking — the costs that priced premiums and the certainty of conversion are designed to meet.182 In 2023 the cost of covering uninsured depositors, about $16 billion, as the FDIC estimated in November 2023, was billed to larger banks rather than to taxpayers.183 The WGFAA makes that the rule rather than the exception.
4.1.4. Governance and Capitalization
Governance and Ownership: The Board of Directors is replaced. Executive leadership responsible for the failure is removed and subject to compensation clawbacks. Who owns the converted bank, and so who chooses its board, depends on its size.
Local and Regional Banks: A local or regional bank becomes the property of its depositors. The receiver moves its business into a newly chartered mutual bank: it has no shareholders, each depositor has one vote, as each member of a credit union does, and the depositors elect the board, with seats reserved for the bank's employees.184 This is an old American form, not a new one. Mutual savings banks and credit unions are owned by the people who bank with them, under charters and regulators that already exist, and community bankers have long worked alongside both.185 Because no official appoints the board, no administration can remove it. The mechanics are close to what the FDIC does now. When it takes over a failed bank it can already move the bank's business into a newly chartered institution, a bridge bank,186 and federal law already provides for savings institutions chartered in mutual form.187 What the Act adds is a mutual charter made for this purpose. The existing federal mutual and credit union charters carry lending limits written for home lenders and for small consumer lenders, and a converted commercial bank that went on lending to businesses would run into them.188 Two other routes are open. A state, a city, or a county may take ownership instead, and then appoints the board together with community stakeholders and employee representatives, loosely modeled on the Sparkassen governance structure. And where a sound credit union already serves the same community, the receiver may transfer the failed bank's accounts and loans to it, the way credit unions already buy banks; that business then operates under the credit union's own charter.189 The Act gives the receiver the power to resolve a failed bank by any of these routes.
The Largest Banks: A bank with more than $250 billion in assets is a national institution with customers in every state, and no single community or body of depositors can speak for it. It becomes a federal public corporation (Section 8.1). Its board is accountable to the public at large: publicly appointed directors serve fixed, staggered terms on the rules in Section 8.1, alongside representatives of employees, of customers, and of the regions where the bank does most of its business. In every case the point is the same. Leadership answers to the people and communities the bank serves, rather than to distant shareholders focused on quarterly earnings.
Capitalization: The cost of this conversion is borne by the financial industry, not the taxpayer. The WGFAA establishes a Public Bank Capitalization Fund, financed by a surcharge on the deposit insurance premiums of the largest private banks (Global Systemically Important Banks, or G-SIBs). At an illustrative rate of 0.10% a year, a surcharge on the roughly $9 trillion in deposits held by the eight U.S. G-SIBs190 would raise on the order of $9 billion annually, a small fraction of those banks' operating costs; JPMorgan Chase alone reported $95.6 billion in noninterest expense for 2025.191 Over five years that builds a standing fund of $45 billion, which, as a rough illustration, could give a bank the size of First Republic a capital cushion of 8% to 10% of its assets twice over, a range equal to the leverage ratio community banks may hold in place of the full risk-based capital rules and well above the 5% leverage ratio that counts as well capitalized. If a wave of failures arrives before the fund has built up, it may borrow up to $75 billion from the Treasury against future surcharge revenue, just as the Deposit Insurance Fund can today.192 This ensures that the institutions creating systemic risk pay for the solution. In many failures, leaving the shareholders and bondholders behind is enough to fill the hole in the balance sheet, because their losses absorb it. Where a gap remains even after that, the fund does not have to write a check for the whole amount on the first day. A Public Benefit Bank may open with the gap on its books, backed by a guarantee from the fund, and close it from its own earnings on a fixed schedule — a bank of $200 billion earning 1% on its assets retains about $2 billion a year. The private banks rescued after 2008 were healed in much the same way, partly by time, guaranteed funding, and retained profits; the difference is that here the recovery belongs to the bank's depositors or to the public, not to shareholders.193 The fund pays cash only if a bank falls behind its schedule, which lets the same surcharge support many more conversions. The Fund also covers legal defense costs arising from conversion challenges. Shareholder litigation is inevitable; the Fund ensures that legal fees do not drain resources from the converted institution's public mission or fall on taxpayers.
The principle is simple: the industry that creates the risk funds the resolution. Taxpayers are held harmless.
G-SIBs will resist these surcharges — that is certain. But the political economy favors this structure. First, the surcharge is framed as insurance, not taxation: banks pay to avoid being on the hook for ad-hoc bailout costs that fall unpredictably and disruptively. Second, the alternative — taxpayer-funded resolutions — faces far greater political opposition in the post-2008 era. Third, G-SIBs already carry systemic-risk capital surcharges under Basel III; the principle that the largest banks pay more for the risk they create is settled, and this applies it to the cost of resolution.194 The WGFAA does not ask Wall Street to fund its competitors out of altruism; it forces them to fund systemic stability because the alternative — chaotic failures or taxpayer bailouts — is worse for everyone, including them.
What Lenders Get: Depositors are covered in full. The bank's lenders are not. Some of them hold collateral: a Federal Home Loan Bank, for example, lends to a bank against mortgages and securities.195 Those lenders must be paid the value of their collateral. This is a requirement of the Constitution, not a favor: a claim on collateral is a property right, and the government may not take property without paying for it (Section 6.1).196 But what they are owed is what the collateral would fetch in the market on the day of failure, which in a crash may be small, and not the amount they lent. The shortfall is their loss. Bondholders and other lenders without collateral are paid only from whatever the FDIC recovers from the failed bank's remaining assets, in the order federal law already sets.197 In many failed bank resolutions, senior secured creditors recover a substantial portion of their claims; general unsecured creditors and subordinated debt holders typically face significant haircuts.198 The government does not pay for creditors' losses. That is what separates this from a bailout. Lenders receive what the assets are worth and no more, and under the WGFAA those assets are put to public use rather than sold to a competing mega-bank.
5. The Technology Solution
5.1. Systemically Important Technology Institutions
Just as the failure of a major bank threatens financial liquidity, the failure of a major AI laboratory or compute provider threatens the digital infrastructure of the 21st century. The WGFAA treats these entities not as standard corporations subject to ordinary bankruptcy, but as Systemically Important Technology Institutions (SITIs): critical public infrastructure in waiting.
5.2. Establishing the Federal Digital Infrastructure Corporation (FDIC-Tech)
The WGFAA creates the Federal Digital Infrastructure Corporation (FDIC-Tech), a new regulatory body (or a specialized independent division within the existing FDIC) tasked with ensuring the stability of the digital economy.
5.2.1. Mandate and Authority
The FDIC-Tech is granted authority to act as the receiver for insolvent SITIs. Its mandate has two sides, and both are written into the statute. The first mirrors that of the FDIC for banks: to maintain public confidence and resolve failed institutions with minimal cost to the taxpayer. The second is to keep access to computing power broad and competitive. An agency charged only with preventing harm learns that "no" is always the safe answer; the FDIC-Tech is also charged with making sure that the nation's computing capacity gets built, used, and widely shared.
Resolution Authority: The WGFAA grants the FDIC-Tech "Orderly Liquidation Authority" (similar to Title II of Dodd-Frank) over technology companies designated as systemically important.199 This allows the agency to place a failing firm in receivership, remove its management, and operate it as a "bridge entity" to prevent systemic contagion. Unlike traditional bankruptcy, which prioritizes creditor recovery, FDIC-Tech resolution prioritizes service continuity and public benefit.
Asset Preservation: The agency is empowered to freeze critical digital assets (code, data, model weights) to prevent their deletion or unauthorized transfer during the resolution process. This includes the power to override contractual "kill switches" or internal policies requiring data destruction upon insolvency. The assets that represent billions in investment and years of research are preserved for public benefit rather than destroyed to satisfy narrow private interests.
A Defined Trigger: A firm is placed in receivership only when it has failed or is on the point of failing. Three events are failure by definition, and each puts a SITI into receivership automatically, with no vote and no official's judgment. The firm files for bankruptcy. It misses a payment of $100 million or more on its debts or leases and has still not paid when the grace period in its own contract runs out, or after 30 days, whichever comes first. Or it takes emergency federal support (Section 6.6). A payment withheld in a good-faith dispute over whether it is owed does not count as missed, and neither does one the lenders have agreed to defer; a firm kept alive on such extensions can still be reached by the early route below. The FDIC-Tech certifies that the event has happened, which is a matter of record, and takes over. Any bankruptcy case then gives way to the receivership, as Dodd-Frank already provides for failed financial companies.200 A company that is paying what it owes cannot be converted under this Act, whatever regulators think of its business model.
Acting Early, with Three Keys: Waiting for one of those events is often waiting too long. By the time a payment is missed, lenders have seized hardware, staff have left, and customers have gone. So the Act also allows receivership when a firm has not yet crossed one of those lines but cannot pay its obligations as they come due, owes more than its assets are worth, or is about to file for bankruptcy. This is the same "in default or in danger of default" standard that Dodd-Frank applies to financial companies.201 Because that is a judgment, and because AI companies are politically sensitive in a way banks are not, no single official may make it. As under Dodd-Frank, it requires a written recommendation from two-thirds of the FDIC-Tech's board and two-thirds of the Federal Reserve Board, and a determination by the Secretary of the Treasury, who must consult the President.202 A president who wanted to put a disfavored company into receivership would need two boards to agree in writing that it had failed, and the members of one of them, the Federal Reserve Board, cannot be removed at will (Section 8.1).203 And an administration that preferred a bailout cannot avoid a conversion by declining to vote, because the automatic triggers do not wait for one.
Fast Court Review: A firm placed in receivership may challenge it in federal district court, whether the challenge is to a finding of failure or to the claim that an automatic trigger occurred. As under Dodd-Frank, the court has 24 hours from receiving the petition, and if it has not ruled by then the receivership goes ahead.204 Its review is limited to whether the finding was arbitrary or, for an automatic trigger, whether the event occurred.205 Owners get their day in court without getting months in which to strip assets.
Automatic Freeze: From the moment the receiver is appointed, and for 90 days after, lenders may not seize or sell collateral, landlords and suppliers may not cancel contracts on account of the insolvency, and counterparties may not trigger cross-defaults. The FDIC has some of the same protection when it takes over a bank.206 Without it, a wobbling firm's lenders would race each other to grab the hardware, and the race itself would finish the firm off.
5.2.2. Technology Stability Oversight Council (TechSOC)
To identify which firms fall under this regime, the WGFAA establishes the Technology Stability Oversight Council (TechSOC). Composed of the heads of the FDIC-Tech, FTC, FCC, CISA, and Treasury, this body monitors the technology sector for systemic risks.
Designation Power: TechSOC has the power to designate firms as Systemically Important Technology Institutions (SITIs) based on their size, interconnectedness, and the lack of substitutability of their services. A firm providing AI infrastructure to hospitals, financial institutions, and government agencies — infrastructure that cannot be quickly replaced — could meet the criteria for this designation.
Criteria for Designation: As with the bank rules, the criteria are written down in advance rather than left to discretion.207 A firm is presumptively a SITI if it meets any one of the following:
Scale: it owns or operates 3% or more of the nation's registered AI computing capacity (measured through the chip registry described in Section 5.4), or has more than $10 billion in annual revenue from AI and cloud services, or more than 50 million monthly users in the United States
Critical dependency: it is the primary AI or computing provider for 25 or more hospital systems, electric or water utilities, systemically important financial institutions, or federal agencies — a count made possible by requiring those customers to report their providers
Interconnectedness: it owes more than $25 billion in debt and lease obligations to U.S. banks, insurers, pension funds, and credit funds
Lack of substitutability: TechSOC finds, on a written record, that no alternative provider could absorb the firm's critical customers within 90 days of a failure
A firm that meets a threshold may contest its designation by showing that its failure would not in fact disrupt critical services or the financial system, and TechSOC must answer that showing in writing. Vague criteria do not survive in court: in 2016 a federal judge threw out the designation of MetLife as systemically important208 in part because regulators had not adequately explained their reasoning.209 Hard numbers, a written record, and a right of reply are what make a designation stick.
5.3. The SITI Conversion Protocol: From Failure to Public Utility
Unlike the Dodd-Frank Act, which requires large banks to write "living wills" planning for their own orderly resolution (death), the WGFAA mandates Conversion Planning for SITIs.210 These institutions provide infrastructure that cannot be allowed to simply "die" or be liquidated piecemeal. SITIs must operate with the clear legal understanding that insolvency results in immediate conversion to a public utility.
5.3.1. The "Public Utility" Trigger
Receivership: When a SITI fails, whether by one of the automatic triggers or by the three-key determination in Section 5.2.1, it is placed in receivership with the FDIC-Tech. This is receivership, not conservatorship: a conservator holds a firm for its owners and hands it back when it recovers, as with Fannie Mae and Freddie Mac after 2008, while a receiver ends the owners' interest and passes the working institution to a new owner. The receiver's mandate is to maintain operations and service continuity for the public benefit, not to maximize recovery for creditors.
Non-Profit Conversion: The entity is reorganized as a federal public corporation with no shares (Section 8.1), as a Public Compute Utility or a Public Research Institute. Its mission shifts from profit maximization to "safe, equitable, and open access" to digital resources. The profit motive that incentivized reckless deployment and safety shortcuts is removed.
5.3.2. The "CERN for AI" Model (Public Research Institutes)
For failed frontier AI labs (e.g., a hypothetical insolvent OpenAI or Anthropic), the conversion creates a Public Research Institute modeled after CERN (European Organization for Nuclear Research).
Structure: These entities operate as national public research consortiums, governed by boards representing the scientific community, civil society, government, and the workforce. They are insulated from market pressure to ship products before safety testing is complete.
Mission: The profit motive is replaced by a mandate for scientific advancement and safety. The institute focuses on alignment research, interpretability, and the development of "public option" models that are open, transparent, and designed for societal benefit rather than surveillance or advertising optimization.
Open Access: The proprietary models ("weights") held by the failed firm are classified as public goods. Access is granted to academic and non-profit researchers under strict safety protocols, breaking the near-monopoly on frontier AI research currently held by a handful of private firms.211 The public investment that made these technologies possible is returned to the public.
Safety Mandate: Relieved of the pressure to ship products for quarterly earnings, the new institute focuses on the hard problems of AI safety that private firms have under-researched. It serves as the "gold standard" for responsible AI development, pressuring the surviving private sector to raise its own standards through competition on safety rather than speed.
5.3.3. The National Research Cloud (Public Compute Utility)
For failed cloud providers and data center operators, the conversion creates a Public Compute Utility (PCU). Hardware assets are integrated into a National Research Cloud.
Infrastructure Access: The GPUs, data centers, and networking equipment of failed firms provide compute capacity to universities, startups, non-profits, government at every level, and the public at large, at subsidized rates where the mission calls for it. This democratizes access to the raw power needed for AI development, breaking the current oligopoly where only the wealthiest firms can afford frontier-scale training runs.212
Utility Regulation: PCUs operate under public utility regulation. They must offer non-discriminatory access and regulated pricing, preventing price gouging during periods of high demand. They cannot refuse service to qualified researchers or startups based on competitive considerations.
Grid Stability: As public entities, PCUs are mandated to coordinate with energy grid operators to ensure their power consumption does not destabilize the electrical grid or drive up costs for residential ratepayers. Unlike private data centers that externalize energy costs onto communities, public utilities internalize these considerations.
Whole Sites, Not Loose Chips: A GPU is useless without a powered building, cooling, networking, and the people who know how to run it all. The National Research Cloud therefore takes over complete working data centers, with their staff, that it can operate from the first day — not pallets of hardware that would sit in a warehouse. Loose chips and sites the utility does not need are sold to private buyers under the rules in Section 5.4.
No Ceiling, and No Hoarding: The goals of the National Research Cloud are to maintain the nation's computing capacity through a crash, to keep services running, and to widen access to computing power. None of those goals is served by an arbitrary limit on its size, and the statute sets none: the FDIC-Tech may acquire any failed firm's working capacity. What the statute does impose is a rule against hoarding. A crash means there are more chips than customers, and idle chips burn electricity while earning nothing. The utility therefore runs what has users and may power down what does not, but capacity left idle for more than 30 days must be offered for sale to buyers under the concentration cap (Section 5.4.5). Capacity that is down for planned maintenance, or already committed to a customer, does not count as idle. The short clock is deliberate. It keeps the government from simply failing to switch a data center on. If there is truly no demand for computing, nobody will want the chips, and the offer costs nothing. If someone does want them, the utility either puts the capacity to work or sells it, and because the dominant firms are barred, the buyers will be smaller competitors. The public holds capacity in order to use it, not to keep it off the market.
An Anchor Customer: The federal government spends billions of dollars a year renting computing power, including from213 the same three companies that dominate the market.214 The WGFAA directs federal agencies to move their AI and general computing workloads onto the National Research Cloud as its capacity and security certifications allow. This gives the utility steady revenue from its first day, and every dollar moved is a dollar that no longer reinforces the dominant firms. The Tennessee Valley Authority grew the same way: it sold power commercially, and the federal government was among its largest customers.215
Staying Current: AI chips age quickly. Hardware bought in a fire sale is top of the line only until the next chip architecture arrives (the annual releases in between are mid-generation refreshes), and it is written off over five or six years. The utility's charter therefore requires it to set aside a fixed share of its enterprise-tier revenue (Section 9.4) for replacing hardware, so that the public's computing power does not decay into a museum.
5.4. Compute Licensing and the Chip Registry
Converting failed SITIs is not enough to keep a crash from concentrating computing power. Most of the companies that would fail in an AI bust are not individually systemic; their hardware would pass through ordinary bankruptcy or lender foreclosure, and the natural buyers are the three or four hyperscalers that already own most AI chips.216 The WGFAA therefore sets a small number of rules for who may own and buy large clusters of advanced AI chips. They are administered by the FDIC-Tech, not by a new agency.
5.4.1. What the Rules Are For
The rules have three jobs. They keep a fire sale from handing the nation's best chips to the companies that already control the most computing power. They give the public first pick of failed firms' data centers. And they make sure that chips from a liquidated cluster do not quietly disappear abroad.
On the last point, no new export regime is needed. Exporting advanced chips to China and other countries of concern already requires a Commerce Department license, and a lender who forecloses on chips cannot lawfully ship them there.217 The gap is smuggling. It already happens, through shell companies, false paperwork, small resellers, and shipment through third countries; federal prosecutors have brought cases involving hundreds of chips and servers at a time,218 and investigators believe the documented cases understate the traffic.219 Once a chip has been sold inside the United States, no law requires anyone to know where it is. A 2023 executive order would have required the largest clusters to report to the Commerce Department,220 but it was rescinded in January 2025 before the rule took effect.221 A fire sale — thousands of chips sold in small lots by liquidators whose only goal is cash — is the smuggler's ideal market.
5.4.2. The Registry
The FDIC-Tech keeps a national registry of large AI computing clusters: who owns each one, where it is, and who holds loans against it. The model is the Federal Aviation Administration's aircraft registry, which has recorded the ownership of, and the liens filed against, every civil aircraft registered in the country for decades.222 It is a database, not a permission system. The FDIC-Tech needs the same information anyway to set premiums, designate SITIs, and plan resolutions.
Threshold: Registration applies to anyone who owns or operates 1,000 or more advanced AI accelerators, defined by a stated level of computing performance rather than by maker or model. Chips a company designs for its own use count the same as chips it buys: Google's and Amazon's in-house accelerators are among the largest single blocks of computing power in the country, and a registry that counted only chips bought from outside suppliers would measure both firms at a fraction of their real capacity.223 Below the line nothing applies. Gaming cards, workstations, university labs, and small company clusters are never touched.
Owner and Operator: Ownership of the hardware and control of it are coming apart. Nvidia has arranged with six of the largest investment managers to raise more than $500 billion through financing vehicles that would hold title to chips and lease them to the companies that run them,224 and chips leased from one company to another already exist.225 The registry therefore records both the entity that holds title to a cluster and the entity that operates it, and a lease of registered capacity is itself recorded. A map that showed only the legal owners would be accurate and useless.
Once Registered, Always Tracked: A size threshold invites an obvious trick: break a big cluster into small lots and every lot falls below the line. So chips that have ever been part of a registered cluster stay on the registry by serial number through every resale, whatever the size of the lot — the way a car title follows the car. A startup or university buying a rack of used chips from a registered cluster files a free online notice; there is no license, no fee, and no waiting period.
Early Warning: Restarting a dark data center is far harder than keeping a live one running, and by the time a small operator reaches liquidation its staff may be gone and its machines cold. The owner of a registered cluster must therefore notify the FDIC-Tech when it defaults on a loan secured by the cluster, or when it has less than 60 days of operating cash. Every SITI gives the same notice, whether or not it owns a registered cluster. The notice is confidential. It gives the public time to exercise its first option (Section 5.4.6) while the site is still running.
Better Technology When It Exists: Congress is considering bills that would require advanced chips to be able to verify their own location.226 If that becomes law, the registry will use it. The registry does not depend on it.
5.4.3. The Owner License
Owning or operating a registered cluster requires a license. The license attaches to the owner, once — not to each chip, each site, or each use — and it is "shall-issue": an owner that meets the published standards for physical security, cybersecurity, and reporting gets the license. The FDIC-Tech does not review what is run on the chips.
The precedents are familiar. From 1946 to 1964 all fissionable material in the United States was owned by the government by law, and private reactors leased it.227 Today a lender may hold a lien on a nuclear plant but may not take possession of it without the regulator's consent,228 and a broadcast license cannot change hands without the approval of the Federal Communications Commission.229 Proposals to account for advanced chips in the way nations account for fissile material are now part of the mainstream debate over AI security.230 The WGFAA borrows the narrowest piece of those regimes: control over who may hold the hardware.
This is deliberately not a safety regime for what AI systems do. That is a separate and much larger question, and folding it into a crisis-resolution statute would do justice to neither.
5.4.4. Not Another Nuclear Regulatory Commission
The Nuclear Regulatory Commission is a warning as much as a model. It reviews applications case by case,231 works without binding deadlines,232 bills applicants by the hour,233 and has a mandate centered on safety, under which refusing is always the safe choice.234 Each of those failures is designed out:
- Bright lines: below the threshold nothing applies, and above it the standards are published in advance
- Clocks: the parties to any transfer of a registered cluster, or of control of a SITI or of a company that owns a registered cluster, file a notice, and the transfer goes ahead after 30 days unless the FDIC-Tech objects in writing — the way the great majority of mergers clear antitrust review today235
A two-sided mandate: the FDIC-Tech answers for access to computing power as well as for stability (Section 5.2.1)
No hourly fees: the regime is funded from the compute levy (Section 9.2), so the agency has no financial interest in a long review
Discretion in one place only: a healthy company selling to another healthy company below the cap files a notice and moves on; real judgment is exercised only when the seller has failed or has warned that it is about to
5.4.5. The Concentration Cap
No company that controls more than 5% of the nation's registered AI computing capacity may acquire compute assets out of a bankruptcy, a receivership, or a lender's foreclosure. Capacity is charged to the company that controls its use: a cluster leased from a financing vehicle or another company counts against the lessee, not the owner, so that the same chips are never counted twice. The rule is written into the statute and enforces itself; it needs no case-by-case approval. A sale that breaks it is void, not merely challengeable, and it does not depend on any administration choosing to enforce it: the receiver, any rival bidder, and the attorney general of any state may sue to void the sale and recover the assets.
The model is the nationwide deposit cap, which bars interstate acquisitions that would leave one bank holding more than 10% of deposits at insured institutions nationwide.236 That cap has one fatal flaw: an exception for acquiring a failing bank,237 which is how JPMorgan Chase, already over the cap, was allowed to absorb First Republic in 2023.238 The WGFAA cap has no such exception. A failing seller is the case it exists for. The Act repeals the banking exception as well (Section 4.1.2).
The cap limits one thing: buying the wreckage. A capped company may still buy as many new chips as it likes from manufacturers and go on growing, and in a glut it will not be short of supply.
Two ways around the cap are closed. The first is leasing. A small company under the cap could buy distressed chips and lease them straight to a giant, which would then control them as surely as if it had bought them. So capacity acquired in a distressed sale may not be leased to a capped company, or dedicated to its use under contract, for five years after the sale, which is most of a chip's working life. The second is getting there first. A giant that cannot buy a failed firm's assets can buy the firm a month before it fails. So once a company has given its early-warning notice (Section 5.4.2), neither its registered clusters nor control of the company may pass to a capped company, whether by purchase, by merger, or by a deal to hire its staff and license its technology. The notice is confidential, so the bar is applied when the parties file their transfer notice (Section 5.4.4): the FDIC-Tech must object. A deal that breaks either rule is void on the same terms as a sale that breaks the cap.
5.4.6. Distressed Sales
When a registered cluster is sold out of a bankruptcy, a receivership, or a foreclosure — whether or not the seller was ever designated a SITI — the following order applies:
The public goes first. The assets are offered for sale to every eligible buyer, and the FDIC-Tech has a right of first refusal, exercisable within the 30-day notice period, to acquire them for the National Research Cloud by matching the best eligible bid. It never pays less than the asset-based price defined in Section 7: where the best bid is lower than that price, or there are no bids, it pays the Section 7 price. The purchase is paid for from the Digital Stability Fund, and the public takes whole working sites. A bidder whose winning bid is matched is reimbursed its reasonable costs of bidding, as the opening bidder is in an ordinary bankruptcy sale, so that the public's option does not discourage others from bidding at all.
Buyers under the cap go second. Everything the public does not take is sold on the open market to licensed buyers below the 5% line: mid-size cloud companies, startups, universities, and ordinary businesses. Cheap hardware in their hands builds real competitors to the dominant firms, which the government cannot do alone.
Companies over the cap are barred.
Two Hats, Kept Apart: The seller in these sales and the public buyer must not be the same body. The FDIC-Tech acts as receiver with a duty to the failed firm's creditors; the National Research Cloud is a separate public corporation with its own board (Section 8.1), and it is the Cloud, not the receiver, that decides whether to exercise the public's option and at what price. The FDIC has long worn two hats in the same way, as insurer and as receiver,239 and the courts have accepted the arrangement, treating the two capacities as legally separate.240 Independent appraisal (Section 7.3) and court review of the price (Section 7.5) sit on top of that separation.
Distressed sales of registered chips must run through approved channels. The receiver, trustee, or lender conducting the sale must verify and record every buyer, as banks already must for their customers, and must offer whole sites and large lots before breaking a cluster into small ones. Small-lot sales are the last resort, and they are where scrutiny concentrates.
Lenders keep their rights but not their choice of buyer. A lender with a lien on a registered cluster may still foreclose, but — like the holder of a lien on a nuclear plant — it may not operate the hardware without a license and may sell it only to a licensed buyer under the cap, after the public has had its option.
A paper registry will not stop a determined smuggler with a clean shell company. It will show exactly whose chips went missing — which today nobody could say.
5.5. Community Innovation Hubs
The WGFAA also funds something that does not wait for a crash and has nothing to do with data centers: places for people to work. A Community Innovation Hub is a building — a community center for starting things. Residents who meet simple criteria sign up for a free membership: people starting a business, freelancers, students, workers retraining after a layoff, local nonprofits. They get a desk, meeting rooms, fast internet, workshops and classes, mentors, small-business counseling, and, above all, other people doing the same thing in the same room.
These places already exist, and they work. The efactory in Springfield, Missouri, run by Missouri State University,241 opened in 2013 in a converted downtown building with the help of a $2.75 million federal grant awarded in 2009.242 It offers coworking space, offices, an accelerator, and training.243 Its clients have gone on to create roughly 3,000 jobs as of its 2023 tenth anniversary and raise $153 million in investment,244 and it has since added a third coworking space.245 There are hundreds of similar hubs across the country, in old mills, libraries, and storefronts, run by universities, cities, and nonprofits.246
What the United States has never done is build them at scale.247 China did. Its "mass entrepreneurship and innovation" campaign, launched in 2015,248 helped give China nearly 15,000 startup incubators, the most in the world,249 and changed the country's culture around starting a company.250 It also offers a warning: local officials chasing subsidies opened spaces that sat empty, and many closed once the money moved on.251 Federal support in the United States errs in the other direction. The main program for this purpose, the Economic Development Administration's Build to Scale, is funded at about $50 million a year, for grants ranging from the low hundreds of thousands of dollars up to $5 million; the Small Business Administration's 2025 accelerator competition gave first-stage prizes of $75,000;252 and the regional Tech Hubs program was authorized at $10 billion but has received a small fraction of that.253 The country knows how to do this. It funds it at a trickle.
Under the WGFAA:
Grants go both to existing hubs and to new ones. Cities, counties, tribal governments, libraries, community colleges, universities, and nonprofits apply, and an established hub with a record of results can apply for money to expand.
Every congressional district is guaranteed at least one funded hub, so that the program reaches rural areas, small cities, and neighborhoods far from any technology industry. The remaining money is awarded competitively.
Grants cover both buildings and operations, run for several years, and require a modest local match that is waived for distressed communities.
Funding follows use, not square footage. Hubs report their membership, the businesses started, and the jobs created, and renewal depends on those numbers — the lesson of China's empty incubators.
The program is run by the Economic Development Administration, which already makes grants of exactly this kind, not by a new office.
Each hub is governed locally. Where a Public Benefit Bank operates in the same community (Section 4), the two work together: the hub helps a business get started, and the bank lends to it. If a National Research Cloud comes into being (Section 5.3.3), hub members are a natural first audience for its low-cost tier, but the hubs do not depend on it.
The hubs are paid for by the industry, from the day the Act takes effect. When cable television was built out, cities required cable operators — as a condition of using the public's rights of way — to pay franchise fees of up to 5% of their gross cable service revenue,254 part of which funded community studios where any resident could learn to make television.255 The same principle later connected the nation's schools and libraries to the internet, through the E-Rate program, paid for by telecommunications carriers.256 The WGFAA applies it to the AI industry: a Public Access Fee of 1% of U.S. revenue from AI and cloud services, charged to providers above the SITI revenue threshold (Section 5.2.2), is dedicated by statute to the hubs.
6. Legal Mechanisms for Receivership and Conversion
The implementation of the WGFAA relies on a robust set of legal authorities to carry out the receivership and conversion of failed institutions without lengthy litigation that would allow asset stripping or value destruction.
6.1. Statutory Authority and National Security Review
Direct Statutory Authority: The power to place a failed SITI in receivership and convert it comes from the WGFAA itself. It is tempting to reach instead for the Defense Production Act, but that would be a mistake. The DPA lets the President prioritize contracts and allocate scarce materials; it does not transfer the ownership of a company.257 When President Truman seized the steel mills in 1952 without clear authority from Congress, the Supreme Court reversed him.258 With clear authority from Congress the ground is firm. Congress has written special insolvency regimes for banks, for financial companies,259 and — most to the point — for the bankrupt railroads of the Northeast, whose assets it conveyed in the 1970s to the publicly created Conrail.260 Creditors sued, and the Supreme Court upheld the conveyance.261
What the Constitution Requires: The conversion framework is built to meet four conditions. First, the firm must actually have failed (Section 5.2.1); wiping out the owners of a solvent company would be a taking of their property. Second, secured lenders must receive the value of their collateral, because a lien is property;262 the Supreme Court struck down a New Deal farm-relief law in 1935 for stripping mortgage holders of theirs.263 What they are owed is the collateral's value on the day of failure — not the amount of the loan. Third, every creditor must receive at least what an ordinary liquidation would have paid. Fourth, the courts have the last word on value: Congress cannot make its own price conclusive, so the valuation formula in Section 7 is the government's offer, and a creditor who believes liquidation would have paid more may sue the United States for the difference. The Conrail precedent is a caution here as well as a comfort — after years of litigation over what the railroads' assets had been worth,264 the government settled with the Penn Central estate alone in 1980 for some $2.1 billion.265 In a genuine glut, where liquidation values are low, that exposure is small. It is not zero, and the funds in Section 9 are sized with it in mind.
CFIUS Review: The WGFAA mandates that any proposed sale of a SITI's assets, and any distressed sale of a registered computing cluster, is subject to automatic review by the Committee on Foreign Investment in the United States (CFIUS). This ensures that critical algorithms, training data, model weights, and data centers do not fall into the hands of foreign adversaries. The review occurs automatically; no party need petition for it.
6.2. Shareholder Wipeout and Creditor Discipline
The conversion process ensures that those who financed the bubble — shareholders first, then lenders — bear the cost of its failure, while the public gains lasting assets.
The Shell and the Successor: The FDIC-Tech moves the failed firm's assets and operations — data centers, hardware, software, model weights, customer contracts, and staff — into a new public entity. The old company's shares and its debts stay behind in the shell of the failed firm. The new entity pays the shell the asset-based price defined in Section 7, and that money is distributed to the shell's creditors in order of priority. Whatever debt it does not cover is written off. The government does not assume the failed firm's debts. To do so would be to bail out its lenders, and a bailout of lenders is still a bailout.
Extinguishing Equity: Existing shareholders are wiped out completely. Executive stock options are canceled. This strictly enforces the principle that equity holders — who stood to gain unlimited upside from speculative bets — must bear the full cost of failure. There is no "haircut"; there is a zeroing out.
Secured Lenders: A lender with a lien on hardware or buildings is paid the value of that collateral on the day of failure, as the Constitution requires (Section 6.1), and no more.266 A fund that lent $10 billion against GPUs now worth $3 billion receives $3 billion. The remaining $7 billion becomes an unsecured claim against the shell, where it will recover little or nothing. That loss is not a flaw in the framework. It is the market discipline that reckless lending has escaped for a generation, and the knowledge that it is coming will make credit for speculative build-outs scarcer and dearer long before any crash — which is the point. The choice of how to settle belongs to the receiver, not the lender. The FDIC-Tech may take over a loan and keep making the payments, which makes sense when the collateral is worth more than the debt or the terms are good. It may pay the lender the collateral's current value and keep the hardware free and clear, either in cash or, as a bankruptcy court may already order, in installments with interest over several years. Or it may hand the collateral back and let the lender sell it, subject to the rules on distressed sales (Section 5.4.6). It will choose whichever costs the public least.
Contracts as Collateral: Several of the largest loans behind the build-out are secured by customer contracts as well as by hardware (Section 1.2.5), and a contract is worth something only while the provider keeps delivering.267 Left to a liquidation, a failed provider goes dark, its customers cancel, and the contract is worth little more than what has already been earned. It is the receiver's freeze and the public's money that keep the contract alive. A lender's claim on a contract is therefore fixed at what the contract would have fetched on the day of failure with no rescue, and everything the contract earns afterward, through the receiver's work and the public's investment, belongs to the public entity. The public keeps the failed firm running; it does not, by doing so, make the lenders whole.
Who Is Paid First: Among unsecured claims, the WGFAA fixes the order of payment in the statute, in advance:
Employees, for all earned wages, benefits, and accrued leave
Small suppliers and contractors, for the first $250,000 owed to each
Customers, whose prepaid credits and service contracts are carried over to the new public entity and honored in full — the counterpart of a bank's depositors
Local governments and utilities, for taxes and service bills
All other creditors — banks, bondholders, private credit funds, hedge funds, and private equity — in the ordinary order of priority
Congress sets payment priorities of this kind routinely: wages and taxes already rank ahead of general creditors in bankruptcy,268 and depositors rank ahead of bondholders when a bank fails.269
No Favorites After the Fact: What the FDIC-Tech may not do is decide, once a firm has failed, which creditors deserve to be paid. The 2009 rescue of Chrysler drew lasting criticism because secured lenders were seen to receive less than a favored creditor ranked below them,270 and the perception that Washington picks winners among creditors was said to damage confidence in the rule of law.271 Every preference in the WGFAA is written down before the loans are made, and lenders can price it.
Keeping the Lights On: One exception is practical rather than moral. The receiver may pay in full the creditors it needs in order to keep services running — the power company, critical vendors, the landlord of a site the public entity intends to keep. The FDIC has the same authority under Dodd-Frank, on the same condition: no other creditor may be left with less than a liquidation would have paid.272
Executive Clawbacks: Senior executives and directors who were substantially responsible for the failure must return the compensation they received in the five years before it — salary, bonuses, and the proceeds of stock sales alike. For every senior executive, regardless of fault, bonuses and stock-sale proceeds taken in the two years before the failure are recovered automatically. Leadership that extracted hundreds of millions in compensation while steering the firm toward insolvency does not get to keep those winnings.
This is not punitive; it is the restoration of basic market discipline. In a functioning capitalist system, equity holders accept risk of total loss in exchange for unlimited upside, and lenders accept the risk of loss in exchange for interest. For too long, executives, investors, and creditors in systemically important firms have enjoyed the upside while shifting the downside to the public. The WGFAA ends this arrangement.
Current law already allows a smaller clawback. When the FDIC winds down a failed financial giant under Dodd-Frank, it may recover two years of pay, salary included, from the executives and directors substantially responsible.273 The clawbacks in this Act reach only pay received after the Act becomes law, so in its first five years the window is shorter. That is the version most certain to hold up in court. Courts usually uphold laws that attach new costs to past conduct,274 but in 1998 the Supreme Court barred a law from making a company pay for the health care of coal miners it had stopped employing more than 25 years before, a cost it could not have foreseen.275 An executive paid after this Act passes has been told the terms.
6.3. Intellectual Property Preservation
A key legal challenge in tech bankruptcy is the treatment of intellectual property, which may be the firm's most valuable asset but also poses unique risks.
Preventing Deletion: The WGFAA grants the FDIC-Tech the power to issue "preservation orders" that legally prohibit a failing AI company from deleting data or model weights. This overrides any internal "kill switches," contractual obligations to destroy data upon insolvency, or attempts by management to destroy evidence of safety violations. The assets are frozen in place pending conversion.
Algorithmic Disgorgement Exception: While the FTC has used "algorithmic disgorgement" (forced deletion of AI models) as a penalty for privacy violations, the WGFAA creates a "Public Trust Exception."276 Models trained on illegally gathered data may need remediation, but the underlying model structures and weights can be preserved and "sanitized" for public research use rather than destroyed entirely. The technical knowledge embedded in these systems is not lost; it is redirected to public benefit.
6.4. Leased Data Centers
Much of the physical infrastructure of AI is not owned by the companies that use it.277 As Section 1.2.2 described, a data center is often held by a separate shell company, financed by bondholders, and leased back to the AI firm or cloud provider. Placing the tenant in receivership would deliver a lease, not a building.
The FDIC-Tech therefore holds the powers the FDIC already holds over a failed bank's contracts.278 It may take over a lease on its existing terms. It may reject a lease the public entity does not need, leaving the landlord with an ordinary unsecured claim in the shell. And where a site is essential and its lease was written at bubble-era prices, it may acquire the building from the shell company at the asset-based price in Section 7. Where the shell company exists only to keep a failed firm's debt off its books, the FDIC-Tech may treat the two as one.
A Failed Laboratory's Compute Contracts: The same powers apply in reverse. An AI laboratory that fails will hold contracts to buy computing power worth tens or hundreds of billions of dollars from cloud providers and data center operators, far more than a public research institute can use. The receiver may keep such a contract, renegotiate it, or reject it. It keeps only the capacity the public institute needs, at prices renegotiated to the market after the crash, and the provider's claim for the rest is an unsecured claim in the shell. A provider that cannot survive the loss of that contract is itself resolved under this Act.
6.5. The Pension Protection Facility
The strongest argument for making lenders whole is that their losses are not really theirs. Private credit funds are financed by pension funds, life insurers, and banks.279 Some bailouts of creditors since 2008 have been sold in part as a rescue of retirees.280
The WGFAA answers that argument directly: protect the pensioners, not the loans. Debt held for a pension fund takes the same haircut in the shell as debt held for a hedge fund. Giving it priority would not work in any case. Pension funds are rarely the lender of record — they invest through funds that also hold the money of sovereign wealth funds, billionaires, and insurers, so paying the fund pays them all — and a rule that pension-backed loans get repaid would turn pension money into the favored channel for the most reckless lending in the economy.281
Instead, the Act creates a Pension Protection Facility, financed by the same industry levies as the rest of the framework (Section 9.2) and kept entirely separate from the shell. A pension plan that can document losses arising from a WGFAA resolution may draw long-term loans at the Treasury's own rate or, where benefits to current retirees would otherwise be cut, grants. The Facility protects benefits, not fund balances, and its help comes with conditions: full disclosure of the plan's remaining exposure to private credit, and a ceiling on that exposure in the future.
The Facility is aimed chiefly at state and local pension plans, which are among the largest investors in private credit282 and have no federal backstop of any kind;283 private-sector pensions are already insured by the Pension Benefit Guaranty Corporation.284 The precedent is recent. In 2021 Congress created a Special Financial Assistance program for failing union pension plans,285 which by mid-2026 had approved some $78 billion in aid covering about 1.8 million participants.286 That program rescued retirees from their plans' troubles without rescuing anyone's creditors. Policyholders of life insurers are protected by the guaranty funds that every state already maintains; the insurers' investors, like the banks' bondholders, take their losses.287
6.6. Aid Means Conversion
A firm on the edge of failure does not wait to miss a payment. It asks Washington for help, and a government that would rather not convert it can simply give that help. The Act closes that route with one rule for all emergency support: a firm that needs public money to survive has failed. Any bank, and any systemically important technology company, that receives emergency federal support is placed into receivership and resolved under this Act. Emergency support means a capital injection, a guarantee of its debts, a loan on terms the market would not offer, or the purchase of its assets above their market value. Its shareholders are wiped out, its lenders are paid on the terms in Section 6.2, its executives are subject to clawback, and the institution is converted.
The rule binds every federal agency, and it binds the Federal Reserve by name. The Fed may go on lending against good collateral to solvent institutions through broadly available programs, which is its proper job. It may not create a program whose purpose or effect is to support the debts of failing firms, or the funds that lent to them, outside the terms of this Act.
Ordinary liquidity is not aid. A sound bank borrowing from the Fed's discount window against good collateral, at the posted rate, has not failed. The test is whether the support is something a solvent firm could obtain on the same terms. Nor is a program open to every bank on the same terms aid: deposit insurance does not put a bank into receivership.
Passed in advance, the rule does most of its work by being known. Owners and lenders who know that a rescue means a wipeout have every reason to raise private capital or fix their problems first, and no reason to lobby for a bailout. The Emergency Version, where the rule has to be applied to firms that never expected it, sets out its history and its legal footing at greater length.
7. The Valuation Mechanism
7.1. Protecting the Taxpayer
A critical failure of past bailouts has been the government's willingness to overpay for stakes in distressed financial firms, effectively subsidizing the mistakes of private investors with public funds.288 The WGFAA introduces a strict statutory formula for the acquisition of failed entities that ensures taxpayers get a fair deal.
7.2. The "Asset-Based" Valuation Standard
The government is prohibited from using "market value" or "income-based" valuation approaches, which in a bubble environment are inflated by speculative growth projections and hype-driven goodwill. Instead, the WGFAA mandates an Asset-Based Valuation.
7.3. The Valuation Formula
The price the public entity pays the shell for a failed firm's assets (Section 6.2) is calculated as:
P = TA + IPproven
Where:
P = Purchase Price
TA = Tangible Assets at their orderly liquidation value on the day of failure: what the data centers, servers, and GPUs would fetch in a properly marketed sale over a period of 90 days — not the original purchase price, and not the fire-sale price a forced seller would get in a week. If there is a market glut of GPUs, they are valued at the current depressed market rate. Working data centers are valued as working sites, not as the sum of their parts. The value is set by independent appraisers drawn from a standing panel, on the evidence of actual arm's-length sales: once the chip registry exists (Section 5.4.2), a published index of recorded resale prices by chip model and age; until then, dealer quotations and auction results.
IPproven = Proven Intellectual Property. This is defined strictly as patents and software with demonstrated, historical revenue generation. It explicitly excludes projected future revenue or "potential" applications.
Customer contracts are counted within TA on one rule: at what they would have fetched on the day of failure with no rescue, which for a provider whose customers could cancel on its insolvency is little more than the amounts already earned. Revenue the receiver preserves by keeping the firm running is not paid to the lenders (Section 6.2).
Liabilities are not deducted. The failed firm's debts stay behind in the shell and are paid out of P, in the order of priority set in Section 6.2. Deducting them would leave nothing for the secured lenders the Constitution protects (Section 6.1).
Speculative goodwill counts as zero. The formula gives no value to goodwill, brand value, or "hype." In traditional M&A, goodwill often accounts for the premium paid over fair value; the WGFAA prohibits the taxpayer from paying this premium.
7.4. Implications for Investors
This formula ensures that equity holders and unsecured creditors take a significant loss — as they should in any properly functioning market.
Hardware Realism: If a company spent billions on H100 GPUs that are now worth a fraction of that due to an inventory glut, the government pays the current depressed value, not the purchase price. The company's poor timing is not the taxpayer's problem.
No Payoff for Hype: Investors who bought in at 24x revenue multiples based on future "AGI" promises will be wiped out. The government pays only for the "bricks and mortar" of the digital age — physical infrastructure and proven intellectual property — ensuring the public gets a fair deal on the assets it is acquiring.
Moral Hazard Prevention: By making explicit that speculative valuations will not be honored in a resolution, the WGFAA discourages the bubble dynamics that lead to crisis in the first place. Investors cannot assume that the government will validate their most optimistic projections.
7.5. The Formula, the Courts, and the Licensed Market
The formula is the government's offer, not the final word. As Section 6.1 explains, a secured creditor is owed the current value of its collateral and every creditor is owed at least what liquidation would have paid, and a creditor who believes the formula falls short of that may ask a court to say so. The receiver decides what happens and when, as the FDIC has done in its roughly 90 years as a receiver:289 which loans it takes over, which it pays off, and what it offers. No court may hold up a conversion while it is under way. Courts decide afterward whether a creditor was paid enough, and their remedy is money, not the unwinding of the conversion. To keep hundreds of creditors from litigating the same questions in courts all over the country, every valuation claim under the Act goes to a single designated federal court, as Congress arranged when it created a special court to value the bankrupt railroads' property for Conrail.290 The formula is built to survive that test, because it pays precisely what the courts protect: the value of tangible assets in the market as it actually exists on the day of failure.
That market is shaped by the rules in Section 5.4. Fair value is what a willing and eligible buyer would pay. When the companies that dominate computing are barred from distressed sales, the eligible buyers are the public utility and the mid-size firms under the cap, and the price reflects what the hardware is worth to them rather than what a giant would pay to keep it out of a rival's hands. This is not a device for underpaying, and it cannot be one. Where there is a working market in used hardware, the public cannot durably pay less than that market: the right of first refusal works by matching the best eligible bid (Section 5.4.6), and a lender paid less than its collateral would really have fetched will collect the difference in court. The savings the Act produces do not come from buying hardware cheaply. They come from paying nothing for goodwill and projected revenue, and from writing off the gap between what was lent and what the collateral is worth.
Two rules of compensation law bear on the price, and they pull in opposite directions. Value created by the government's own demand for a property is excluded from what it must pay, so a lender cannot claim a premium produced by the public's bid.291 But courts also disregard a fall in value caused by the government's own project, and a lender whose loan predates the Act will argue that the bar on selling to the dominant firms is exactly that.292 The Act does not depend on winning that argument. Lenders who finance chips after it passes will lend with its rules in view.
8. Governance, Operations, and Democratic Oversight
Converting failed entities into public institutions is only the first step; governing them effectively to serve the public interest is the long-term challenge. The WGFAA establishes governance structures designed to balance expertise, accountability, and democratic legitimacy.
8.1. The Public Corporation Structure
The converted technology companies and the largest converted banks are chartered by the Act as federal public corporations, on the model of the Tennessee Valley Authority: they have no shares, so there is nothing for a later administration to sell, and they may be privatized only by an Act of Congress. Conrail, created by Congress in the 1970s, was sold back to private investors in 1987; the charter is written so that this cannot happen quietly.293 The charter requires the board of directors to serve a specific public benefit purpose. Local and regional banks are not federal corporations: they belong to their depositors, or to a state or city, and choose their boards as Section 4.1.4 describes. The rules below apply to them as well, except that the rule on fixed terms matters only where directors are publicly appointed.
Fiduciary Duty Shift: The charter will explicitly state that the board's primary fiduciary duty is to the public interest — defined as safety, equitable access, local economic development, and scientific advancement — rather than maximizing shareholder value. This legal insulation protects the organization from market pressures to release unsafe products, cut corners on service, or abandon the communities it serves.
Stakeholder Boards: The boards of the federal public corporations will be composed of a diverse mix of stakeholders:
Representatives from the scientific and technical community (for AI institutes)
Representatives from served communities (for the largest banks)
Civil society organizations focused on relevant policy areas
Government appointees ensuring public accountability
Workforce representatives ensuring employee voice
This structure ensures a plurality of perspectives in decision-making and prevents capture by any single interest group.
Five rules apply to every board:
An interim board first. A stakeholder board takes months to assemble, and a converted institution has to open on Monday. The receiver appoints a small professional interim board and a chief executive at conversion, as the FDIC does for a bridge bank, and the permanent board is seated within 18 months.294
Fixed terms, not confirmation fights. Publicly appointed directors serve fixed, staggered terms, with no more than a bare majority from one political party, and a director whose term has ended serves until a successor is appointed. Some boards that depend on Senate confirmation sit half empty for years;295 the Postal Service's board had no confirmed members at all for a stretch in 2016 and 2017.296
Expertise, and no sitting politicians. A majority of every board must have relevant professional experience in banking, computing, or research, and no sitting elected official may serve. Germany's local savings banks came through 2008 well;297 its large regional public banks, whose boards were full of politicians,298 lost tens of billions in the crisis, partly on American mortgage securities.299 The narrow mandate in Section 4.1.3 is the first defense against that; the composition of the board is the second.
Ordinary supervision. A Public Benefit Bank is examined and supervised like any other bank, by the same regulators and to the same standards. Who owns it makes no difference.
No return for the responsible. A director or executive found substantially responsible for a failure may not serve at any institution converted under this Act, in addition to the industry-wide bans regulators can already impose.300
What the Act Does Not Promise: The Act does not promise that the directors of the federal public corporations are beyond a President's reach, because that is no longer a promise Congress can be sure of keeping. In June 2026, in Trump v. Slaughter, the Supreme Court held that officials who exercise executive power must be removable by the President at will,301 and it struck down the protection Congress had given the members of the Federal Trade Commission.302 It kept an exception for the Federal Reserve.303 Whether the directors of a public bank or a public computing utility exercise executive power in that sense has not been decided, and the Act is written to work either way. What protects these institutions is not the tenure of their directors. It is what the statute fixes and no board can change: the mission and the list of barred activities, the rule that nothing can be privatized without an Act of Congress, ordinary bank supervision, and the public record of what each institution does. Local and regional banks are outside the question altogether, because their depositors choose their boards. None of this makes the plan safe from a hostile administration. A President who wanted these institutions to fail could appoint directors who would run them badly, and no statute prevents that. The plan will work under an administration that wants it to work, and it is written for one.
Compensation Structure: To retain talent, particularly for AI research institutes competing with private sector salaries, the WGFAA authorizes competitive compensation bands tied to private sector rates. However, compensation is capped at reasonable multiples of median worker pay, and equity-equivalent structures (such as deferred compensation tied to public benefit metrics) replace stock options tied to share price.
8.2. Civic Data Trusts
To manage the massive datasets held by converted AI firms, the WGFAA establishes Civic Data Trusts.
Fiduciary Stewardship: User data and training data are transferred into a trust structure. The trust owes a fiduciary duty to the data subjects (the public), not to the corporation using the data. Trustees are legally obligated to act in the interest of data subjects, not institutional convenience.
Democratic Governance: The trust establishes mechanisms for public input and democratic oversight regarding how data is used. It can negotiate the terms under which data is accessed for training, ensuring privacy protections and fair treatment of data creators. Unlike the current regime — where users surrender data rights in unreadable terms of service — the trust gives the public a meaningful voice in data governance.
Transparency Requirements: The trust publishes regular reports on data holdings, uses, and access grants. Researchers and the public can understand what data exists and how it is being used, replacing the current opacity with democratic accountability.
8.3. Operational Resilience and Continuity of Service
Keeping a failed bank open over a weekend is a solved problem. Keeping a failed AI company running is harder, for two reasons: a failed bank roughly pays its own way from Monday morning, while an AI company may be losing money every day; and an AI company's most important assets can walk out of the door. The WGFAA prepares for both before any failure occurs.
Continuity Protocols: All SITIs are required to maintain detailed technical documentation, code escrow arrangements, and service continuity protocols for critical APIs, as part of the Conversion Planning described in Section 5.3. If a private SITI fails and enters conversion, these preparations ensure a seamless transition. Customers experience no service interruption; the conversion happens behind the scenes.
Escrowed Access: Whoever holds a system's master credentials can lock everyone else out of it. Every SITI must keep emergency administrative access to its critical systems in escrow with the FDIC-Tech, tested at least once a year, so that the receiver controls the systems from the first hour and the security of model weights does not depend on the goodwill of departing staff.
Keeping the People: At AI companies much of an engineer's pay is stock, and conversion has just made that stock worthless.304 The dominant firms will be recruiting the failed firm's staff by Monday morning. The charter's ban on mass layoffs protects workers from the institution; it cannot stop them from leaving it. From the first day of a conversion, the FDIC-Tech therefore pays retention bonuses from the Digital Stability Fund to the operations, security, and research staff needed to keep services running, and the compensation bands described in Section 8.1 take effect immediately.
Stop the Burn, Keep the Service: Continuity of service does not mean that the public funds a failed company's growth strategy. Most of an AI company's losses come from training the next model and building ahead of demand; serving existing paying customers is far closer to covering its own costs. The receiver halts speculative spending at once, keeps critical users and paying customers running without interruption, and brings free consumer tiers into line with what the public mission can support, by pricing them or limiting them.
Paying as It Goes: The automatic freeze (Section 5.2.1) stops power companies, landlords, and suppliers from cutting off a firm in receivership over its old debts, but they will keep serving it only if they are paid from that day forward. The receiver pays current bills in full from the Digital Stability Fund and its Treasury backstop (Section 9.2). Old bills wait in the shell with the other creditors.
Hosted Services: Many AI labs own little hardware and run on computing power rented from a cloud provider — which, when the lab fails, becomes one of its unpaid creditors. The freeze bars the host from cutting off service; the receiver pays the host for service going forward. If the host is itself failing, the FDIC-Tech resolves the two together.
An Operator of Last Resort: The FDIC does not run the banks it resolves with its own staff. It keeps the failed bank's employees and installs an experienced outside chief executive drawn from a roster vetted in advance. The FDIC-Tech does the same. For deep operational support it turns to the Department of Energy's national laboratories, which already operate the highest-ranked supercomputers in the country and serve as operator of last resort and as a source of seasoned managers for converted computing facilities.305
Safety Standards: Public AI research institutes adopt the highest standards of AI safety testing, interpretability research, and transparency. They serve as the gold standard for responsible AI development, demonstrating that safety and capability are not in tension. Their practices pressure the surviving private sector to raise its own standards through competitive pressure.
Workforce Retention: Converted institutions are prohibited from mass layoffs as a condition of their charters. Workforce retention is part of the public mission. Employees of failed private firms become employees of public institutions, preserving human capital and preventing the brain drain that would otherwise follow a major industry collapse.
9. Economic Viability
9.1. Funding the Digital Commons
A sustainable public banking and AI sector requires a funding model that does not rely on perpetual taxpayer injections. The WGFAA proposes a self-funding ecosystem where the industries creating systemic risk pay for the mechanisms that address it.
9.2. The Compute Tax and Digital Stability Fund
To fund the FDIC-Tech and the ongoing operations of public compute utilities, the WGFAA introduces specific levies on the AI sector.
Compute Tax: A progressive tax is levied on high-end AI chips (e.g., GPUs, TPUs) and large-scale model training runs. This tax targets the excessive use of compute resources, encouraging efficiency while generating revenue from the activities creating systemic risk. Small-scale research and educational use is exempted; the tax falls on industrial-scale speculation.
Digital Stability Fund: Similar to the Deposit Insurance Fund (DIF) that backs FDIC guarantees, SITIs pay risk-based premiums into a Digital Stability Fund. The riskiest actors — those with the most leverage, the most dangerous models, or the poorest safety records — pay the highest premiums. This fund covers the costs of future resolutions, ensuring the program is self-sustaining without general tax revenue.
G-SIB Surcharges: For the banking side, a surcharge on the deposit insurance premiums of Global Systemically Important Banks ensures the financial sector pays for its own stabilization. The largest banks, whose activities create the most systemic risk, bear the greatest cost.
Treasury Backstop: A fund built from annual premiums will be nearly empty in its first years, and a crash will not wait for it to fill. The Digital Stability Fund may therefore borrow up to $100 billion from the Treasury, to be repaid with interest from future levies and premiums within 10 years. If the Secretary of the Treasury certifies to Congress that pending resolutions require more, the line rises to $250 billion and the repayment period to 15 years; Section 9.3 explains when that would happen. This is how the FDIC's own insurance fund is backstopped,306 and how Dodd-Frank funds the resolution of failed financial companies: the Treasury lends, and the industry repays.307 The public's money is at risk for a time. It is not spent.
Legal Defense: Lenders and shareholders will sue. As on the banking side (Section 4.1.4), the Fund pays the cost of defending conversions and of any court judgment that a creditor was owed more than the formula paid, so that neither falls on the converted institutions or on taxpayers.
Pension Protection Facility: A fixed share of the compute tax and of the G-SIB surcharge is set aside for the Pension Protection Facility (Section 6.5), which may also draw on the Treasury backstop.
Registry and Licensing: The chip registry and owner licenses (Section 5.4) are funded from the compute tax. No fees are charged to applicants.
Public Access Fee: A fee of 1% of U.S. revenue from AI and cloud services, charged to the largest providers, is dedicated to the Community Innovation Hubs (Section 5.5), on the model of the franchise fees that funded public access television.308 It is collected from the day the Act takes effect.
9.3. How Big Is the Bill?
No one can know the cost of a crash in advance, but the orders of magnitude can be bounded. Morgan Stanley estimates, in its July 2025 projection, that global data center capex will total about $2.9 trillion through 2028, of which roughly $1.5 trillion, the gap left after hyperscaler cash flows, must come from outside financing — including some $800 billion from private credit.309 The largest technology companies fund their share from profits and unsecured bonds, and they are not going to fail. The debt that could land in a WGFAA resolution sits elsewhere: with the GPU-rental companies, the largest of which alone carried more than $35 billion in debt in mid-2026;310 with the project financings behind the AI labs' and hyperscalers' data centers, which run from roughly $10 billion to nearly $30 billion for a single campus;311 and with the cloud providers that have borrowed heavily against a single customer's promise to pay.312
On that basis New Consensus estimates three scenarios:
Narrow, in which two GPU-rental companies and one AI lab fail: an illustrative $30 billion to $60 billion in debt at face value, though if CoreWeave is one of the two, its roughly $35 billion of debt at June 30, 2026 would on its own put the total above the low end.313
Middle, the GPU-rental sector fails and the labs' project financings default: on our rough estimate, $150 billion to $285 billion, where the high end is the whole stock (about $250 billion of AI project and data-center financing outstanding today plus some $35 billion borrowed against chips) and the low end assumes only about half of it goes into resolution.314
Wide: a major cloud provider fails as well, on our rough estimate $300 billion to $400 billion or more (for scale, large US banks had about $450 billion in AI-related loan commitments at end-2025, which the Chicago Fed treats as a ceiling on direct losses, not an expected loss).315
Those are the lenders' numbers, not the public's. Under the WGFAA the public pays only what the assets are worth on the day of failure (Section 7). How much that is depends on a number nobody can know in advance: what used hardware is worth in a crash. If demand for computing collapses and used chips fetch 20 to 40 cents on the dollar, a rough reckoning from the three cases above puts the public's outlay on the order of $10 billion to $25 billion in the narrow case, $50 billion to $100 billion in the middle case, and $100 billion to $200 billion in the wide case. But the resale market for data center chips is active,316 and before any crash used chips of recent generations have traded well above that.317 On our own rough arithmetic, if hardware holds 50 to 70 cents on the dollar, each of those figures roughly doubles, the middle case reaches something like $100 billion to $200 billion, and the Treasury line has to be raised as Section 9.2 provides. Buildings with secured power connections hold their value better than chips in either case. The public cannot choose the lower number: it pays what the market shows the assets to be worth (Section 7.5). Whichever number turns out to be right, the public receives working assets of that value in return, and the difference between that value and what was lent is absorbed by the lenders who made the loans.
For comparison, Congress authorized up to $700 billion for the Troubled Asset Relief Program in 2008, later reduced to $475 billion by the 2010 Dodd-Frank Act,318 and the FDIC's insurance fund held $161.1 billion as of June 30, 2026.319 The middle case is large, but it is not frightening — provided the Treasury backstop exists to cover it up front. A compute tax of a few percent on annual AI chip sales might raise something like $5 billion to $10 billion a year, which on rough arithmetic would repay the middle case within one to two decades on its own, depending on how far hardware values fall.320 The premiums paid by the largest technology companies have to be set to close the gap, so that the whole is repaid within the 10 to 15 years that Section 9.2 allows.
The Banks: The scenarios above cover the technology companies. The bank side can be bounded from the record, because the FDIC publishes every failure of an insured bank.321 Two different sums are involved.
The first is the hole in a failed bank: the gap between what its assets are worth and what it owes its depositors. The banking industry has always paid for that through the FDIC, and under the Act it still does.322 In the six years from 2008 through 2013, 489 banks failed with $686 billion in assets,323 and the cost to the insurance fund was about $69 billion, a tenth of those assets.324 The five failures of 2023 had $532 billion in assets325 and, on the FDIC's latest estimates, cost about $35 billion: $18 billion charged to the insurance fund,326 and about $17 billion billed to large banks through a special assessment.327 Insuring every deposit raises that bill somewhat, because large depositors no longer share in the loss, which is why the premiums rise with it (Section 4.1.3).
The second sum is new: the capital a converted bank needs in order to keep operating. At 8% to 10% of assets, a wave the size of 2023 would call for $43 billion to $53 billion, and one the size of 2008 through 2013 for $55 billion to $69 billion spread over six years. In ordinary years the figure is close to nothing: from 2014 through 2022 about five banks failed a year on average, with under $2 billion in assets among them.328 This is capital, not a loss. It stays inside a working bank, and much of it never has to be paid in cash, because a converted bank may open with a gap on its books and close it from earnings (Section 4.1.4). The capitalization fund, at about $9 billion a year, is sized for a wave like 2023; a larger one draws on its Treasury line of up to $75 billion (Section 4.1.4), which is enough for a wave the size of 2008 through 2013.
One case is of a different order. In 2008 and 2009 the government kept the banks of Citigroup and Bank of America open with federal assistance;329 together they held $3.2 trillion in assets.330 Under this Act, where aid means conversion (Section 6.6), a bank in that position is converted, and 8% of $3.2 trillion is about $256 billion. No fund built from premiums covers that, and none is meant to. The eight largest banks are required to carry their own cushion: capital and long-term debt equal to at least 18% of their risk-weighted assets, with long-term debt alone at least 6% plus a surcharge set for each bank, issued for the stated purpose of absorbing losses when the bank fails.331 When such a bank is converted, that debt is left behind in the receivership (Section 4.1.3), and writing it off is what recapitalizes the bank. The capitalization fund stands behind that debt. It does not replace it.
9.4. Revenue Generation
Public utilities are not profit-maximizers, but they can and should be revenue-positive. The WGFAA structures converted entities to generate operating revenue that sustains their public mission.
Tiered Access Pricing: Public Compute Utilities charge commercial rates to enterprise users while offering subsidized or free tiers to academic researchers, non-profits, small businesses, government at every level, and members of the public. The revenue from enterprise clients cross-subsidizes the public access mission. Large corporations pay market rates; researchers and startups get affordable access.
Federal Workloads: As federal agencies move their computing onto the National Research Cloud (Section 5.3.3), the billions they now spend on IT including commercial cloud become the utility's most dependable source of revenue.332
Licensing and IP: Public Research Institutes can license non-critical intellectual property and applications to the private sector, generating revenue to fund further research. Safety-critical technologies remain open; commercial applications can be licensed. This model mirrors successful technology transfer from universities and national laboratories.
Service Fees: Public Benefit Banks generate revenue through traditional banking operations — the spread between deposit rates and loan rates. Unlike shareholder-owned banks, this revenue is reinvested in the bank's mission rather than distributed to shareholders. The Bank of North Dakota has operated for over a century,333 profitably in recent decades while serving its public purpose.334
9.5. Economic Stabilization Effects
Beyond funding their own operations, public utilities provide stabilizing counter-cyclical forces that benefit the broader economy.
An Orderly Hardware Market: Receivership stops the disorderly race in which lenders grab and dump hardware, and the rules for distressed sales (Section 5.4.6) replace it with a sequence: the public takes the working sites it needs, and the rest is sold promptly to buyers under the cap. The aim is an orderly sale, not a propped-up price. If computing power becomes cheap after a crash, that is a gain for every researcher, startup, and business that uses it — not a harm to be prevented for the benefit of chip makers and their lenders. It would be wrong to pretend that the public is a neutral presence in that market. A buyer with no limit on its size, a Treasury credit line, and the first option on every distressed sale puts a floor under prices whether it means to or not, and the Act wants things that pull against each other: low prices for the public and for smaller competitors, low recoveries for the lenders, and large public holdings. The rule that keeps these in balance is the one against hoarding (Section 5.3.3). The public buys what it can use, and what sits idle for 30 days goes back on the market. The experience of the Resolution Trust Corporation, which sold off the assets of the failed savings and loans,335 cuts both ways — it has been criticized both for dumping assets into a falling market336 and for letting an overhang of unsold property depress prices337 — and the lesson is to sell steadily, neither all at once nor never.
Workforce Retention: Converting failed labs into public institutes prevents the "brain drain" of talent to foreign competitors or alternative industries. High-skilled AI researchers remain employed in the service of the national interest rather than departing for positions abroad. The human capital that represents decades of training and heavy educational investment is preserved.
Credit Continuity: Public Benefit Banks maintain lending to local businesses and consumers during downturns, when private banks typically tighten credit. This counter-cyclical lending supports economic recovery rather than deepening recession. The Sparkassen model demonstrated this during 2008; the WGFAA brings it to America.338
Compute Access Continuity: Public Compute Utilities ensure that researchers and startups retain access to AI infrastructure even during market turmoil. Innovation does not halt because private compute providers have failed; the public infrastructure keeps the engines running.
10. Conclusion
10.1. Seizing the Moment
The bursting of the AI bubble may be inevitable, but it need not be a catastrophe. It presents a rare historical opportunity to correct the structural flaws of the digital economy and the failed patterns of crisis response that have left America more fragile after some economic interventions.339
For too long, the United States has allowed the critical infrastructure of the future — both financial and technological — to be governed by short-term speculation and the accumulation of private power. When these speculative ventures fail, the public has often absorbed the losses while the assets have flowed to ever-larger private monopolies.340 We have socialized the risks and privatized the gains, leaving ordinary Americans to bear the costs of instability while a small elite captures the benefits of public support.
The Won't Get Fooled Again Act offers a different path.
By converting failed banks, we restore fairness and local control to the financial system. Communities get institutions that serve their needs rather than the demands of distant shareholders. The cycle of consolidation ends. The "too big to fail" problem shrinks rather than grows.
By converting failed AI companies, we ensure that the most powerful technology of our time is developed as a public good. Research proceeds on safety rather than speed. Access is democratized rather than monopolized. The public investment that made these technologies possible returns to the public.
By funding these conversions through industry levies rather than taxpayer bailouts, we preserve America's borrowing capacity for productive investment. The fiscal space we would otherwise squander on speculator rescues remains available for infrastructure, industrial policy, climate adaptation, and the public services that build shared prosperity.
By barring the dominant firms from the fire sale and giving the public first pick, we make sure a crash leaves computing power more widely held, not less.
By refusing to pay for speculative goodwill and hype — and by paying lenders only what their collateral is worth — we restore market discipline. Investors and lenders learn that their most optimistic projections will not be validated by public funds. The moral hazard that has distorted American capitalism for a generation begins to unwind.
We are proposing to build the Tennessee Valley Authority of the 21st century — not for dams and electricity, but for data and intelligence. The TVA transformed a region mired in poverty into an engine of American industry.341 It demonstrated that public enterprise could succeed where private speculation had failed. It remains, nearly a century later, a testament to what Americans can build when we choose public purpose over private extraction.
The tools are available. The legal precedents exist.342 The fiscal necessity is urgent. The only missing ingredient is political will.
The speculators have had their chance. They have built a house of cards on circular investments and borrowed money, extracting billions for themselves while creating systemic risks that threaten the entire economy. When their house of cards collapses we must be ready with something better than another bailout that restores the same fragile system.
We must be ready to convert their wreckage into our foundation.
The Won't Get Fooled Again Act is that foundation. It transforms crisis into opportunity, failure into infrastructure, and the end of a bubble into the beginning of a more stable, more equitable, and more productive digital economy.
11. Appendix: Comparison of Resolution Regimes
| Feature | Current Regime (Bankruptcy/Bailout) | Proposed WGFAA Regime (Public Conversion) |
|---|---|---|
| Primary Goal | Maximize creditor recovery / Prevent immediate contagion | Maintain critical infrastructure & public benefit |
| Asset Fate | Sold to highest bidder (often a larger competitor, increasing consolidation) | Converted: a Public Benefit Bank (owned by its depositors, or by the public above $250 billion), a Public Compute Utility, or a Public Research Institute |
| IP/Data Treatment | Monetized or sold (national security and privacy risks) | Placed in Data Trust (security preserved, public access enabled) |
| Management | Often retained; severance sometimes paid343 | Removed; compensation clawbacks enforced |
| Shareholders | May receive residual value; often partially protected | Wiped out completely; market discipline enforced344 |
| Lenders | Sometimes made whole to stop "contagion"; repo lenders free to seize and sell collateral345 | Paid current collateral value only; remainder written off; collateral frozen at receivership |
| Workers, Small Suppliers, Customers | Wait in line behind secured lenders | Paid first, by statute |
| Pensioners | Used as a political argument for bailing out lenders | Protected directly through the Pension Protection Facility |
| Chips and Data Centers | Sold to the highest bidder; no universal record of where chips go | Public first option; dominant firms barred; every chip from a large cluster tracked through resale346 |
| Community Investment | None | Community Innovation Hubs — free places to work and start a business — in every congressional district, funded by an industry fee |
| Funding Source | Ad-hoc bailouts (taxpayer risk) | Industry-funded Digital Stability Fund, with a Treasury credit line repaid by industry |
| Market Structure Effect | Increases concentration (consolidation) | Increases competition (public option) |
| Fiscal Impact | Depletes borrowing capacity for future needs | Preserves fiscal space for productive investment |
| Service Continuity | Often uncertain; dependent on acquirer or wind-down trustee | Guaranteed; continuity is primary mandate |
| Workforce | Layoffs typical in restructuring | Retention mandated; brain drain prevented |
| Long-term Public Benefit | None; status quo restored | Permanent public infrastructure created |
12. Appendix: How This Plan Differs from the Emergency Version
This document describes the Act as it should be passed: in advance, before anything fails. A companion document, the Emergency Version, sets out the same Act for a crash that has already begun. The goals and the design are the same in both: convert what fails, make the people who financed the bubble bear its cost, protect workers and depositors, keep the largest firms from buying the wreckage, and make the industry pay. Everything that differs comes from one fact. This plan has time to prepare, and the Emergency Version does not.
What triggers conversion — The same in both versions: a firm files for bankruptcy, leaves a large payment unpaid, takes emergency federal support, or is found to be about to fail. What differs is which trigger matters. Passed in advance, the rule that aid means conversion works mostly by being known. In a crisis it does most of the work, because the firms that matter come asking for help before they fail.
Where the money comes from — This plan: premiums and levies collected for years, with a $100 billion Treasury credit line behind them. Emergency Version: a $250 billion Treasury credit line, and up to $75 billion more for bank conversions, pays for everything up front, and the industry repays it over 10 years or more.
Who is barred from buying distressed chips and data centers — This plan: any firm with more than 5% of the nation's registered AI computing capacity. Emergency Version: the five largest cloud providers by revenue, until a registry exists to measure shares.
When the rules start — This plan: on enactment, with time for firms and lenders to adjust. Emergency Version: on the day the bill is introduced, with the power to unwind sales to the dominant firms made since the crisis began.
Who acts as receiver for technology companies — This plan: the FDIC-Tech. Emergency Version: the FDIC itself from the first day, with the FDIC-Tech set up within 18 months.
How firms are designated as systemically important — This plan: by a council of regulators, in advance, on a written record, with a right of reply. Emergency Version: by numeric thresholds written into the statute and applied within days.
Preparation inside the firms — This plan: conversion plans, escrowed system access, and continuity protocols. Emergency Version: none of that exists, so it relies on criminal penalties for sabotage, a 24-hour deadline for handing over access, and wider retention pay.
The deposit guarantee — This plan: priced in advance through risk-based premiums. Emergency Version: immediate and free at first, by Act of Congress, with the cost billed to the banks afterward.
Companies already in bankruptcy — This plan: not an issue, because a firm's bankruptcy filing itself puts it into receivership. Emergency Version: pending bankruptcy cases are moved to the receiver, much as Congress required pending reorganizations of the railroads that became Conrail to proceed under a single federal plan.347
The lenders — This plan: they know the rules when they lend, and price them in. Emergency Version: they did not, so their legal challenges are stronger and the credit line is sized for losing some of them.
The chip registry, licensing, and Community Innovation Hubs — This plan: in place before any failure. Emergency Version: the same rules, phased in over the 18 months after enactment, with an emergency census standing in for the registry.
Cost to the public — This plan: lowest. Emergency Version: higher, because assets have been lost or sold, staff have left, the public advances all of the money, and the lawsuits are harder.
The Emergency Version contains several sections this plan does not need: banking measures for a crisis already under way, designation by statute, what stands in for the chip registry, the treatment of cases already in bankruptcy, the added legal risk of acting late, continuity without preparation, and a schedule of what takes effect when. It replaces this plan's opening argument that a bubble exists with a short description of the crash, since in a crash nobody needs persuading.
New Consensus